NEWS
NCDMB, Dangote Push for Sustainable Nigerian Content

From Mike Tayese, Yenagoa
The Nigerian Content Development and Monitoring Board (NCDMB) and the Dangote Group have urged a decisive transition from mere regulatory compliance to a stronger national commitment anchored on technological innovation and sustainable financing.
They emphasized that these pillars are critical to deepening Nigerian content and driving accelerated industrial growth.This call was made during a strategic retreat of the NCDMB/Dangote Joint Technical Committee (JTC), held in Lagos on Friday under the theme “Beyond Compliance: Partnering for Sustainable Nigerian Content Development.
” The retreat convened key stakeholders from the oil and gas sector alongside representatives of relevant government institutions, fostering collaboration to tackle operational challenges and broaden indigenous participation across Nigeria’s energy value chain.At the heart of the discussions was a shared imperative: to ensure that Nigerian content transcends statutory obligations and becomes a sustainable national economic strategy that creates jobs, develops technical expertise, strengthens local supply chains and retains greater value within the country.
In his keynote address, the Executive Secretary of NCDMB, Engr. Felix Omatsola Ogbe, represented by the Senior Technical Adviser and Director of the Project Certification and Authorisation Director (PCAD), Engr. Austin Uzoka, identified commitment, technology and financing as three fundamental requirements for building a resilient Nigerian content ecosystem.
He challenged stakeholders to look beyond compliance and confront the deeper questions of industrial sustainability, particularly how Nigeria could maintain its major industrial assets, strengthen domestic supply chains and ensure that investments in critical infrastructure deliver lasting economic value.
Drawing attention to the challenges associated with the country’s publicly owned refineries, Ogbe, emphasised the need to safeguard the sustainability of the Dangote Refinery by developing the goods, works, services and supply-chain capabilities required to support its continuous operations. The central message was clear: constructing world-class industrial facilities is only part of the task; building and maintaining the indigenous capabilities that sustain them is equally important.
He stressed the need for credible supply chains capable of supporting industrial facilities, developing local capabilities and ensuring that such expertise remains resident in Nigeria. Without reliable domestic supply chains, he warned, the economic benefits of industrial investments could continue to flow outside the country, limiting local value creation and value addition.
On technology, the Executive Secretary underscored the importance of developing Nigerian expertise to operate, maintain and sustain industrial facilities, rather than relying indefinitely on external capabilities. He also highlighted access to financing as a major constraint facing indigenous businesses. High interest rates and delays in accessing funds, he noted, can prevent Nigerian enterprises from executing projects, expanding operations and competing effectively within the oil and gas value chain.
Beyond its regulatory responsibilities, NCDMB used the retreat to reiterate its commitment to creating an enabling environment in which Nigerian businesses can participate meaningfully, build technical competence and compete for opportunities across the oil and gas industry.
In his presentation, the Director of Planning, Research and Statistics (DPRS) and Chairman of the NCDMB/Dangote Joint Technical Committee, Omomehin Ajimijaye, urged contractors, vendors and service providers operating within the Dangote business ecosystem to comply with Nigerian content requirements, register on the designated digital platform, NOGICJQS and strengthen their participation in the industry.
Ajimijaye explained that the Board’s regulatory framework was designed to facilitate business growth and deepen indigenous participation, rather than create unnecessary bureaucratic bottlenecks. He identified four key compliance pillars: Nigerian content planning, workforce localisation, local procurement and capacity development.
Under these requirements, companies bidding for projects are expected to submit Nigerian content plans demonstrating how they will maximise indigenous participation. Employers must prioritise qualified Nigerians, procure locally available goods and services, and invest in skills development and technology transfer.
On expatriate employment, he explained that foreign personnel could be engaged where genuine skills gaps existed, but companies were expected to work with the Board to establish those gaps and develop succession plans that would progressively prepare Nigerians to assume such positions.
He described NOGICJQS as an important digital tool for supplier registration, prequalification, capacity verification and validation of technical expertise. Reliable industry data, he added, would help NCDMB identify skills shortages, connect businesses with qualified professionals and direct training investments towards areas of greatest need.
Ajimijaye commended Dangote Group for its collaboration with the Board since around 2019 in building capacity of Nigerians through local and overseas institutions, noting that some beneficiaries had subsequently secured employment within the group’s businesses.
However, he noted that in-country value retention stood at approximately 61 per cent, below the 70 per cent target, and called for stronger collaboration among regulators, operators and service providers to close the gap.
In his address, the Group Vice President of Dangote Group, Dr. Edwin Devakumar, called for a fundamental shift from a compliance-driven approach to a culture of national responsibility, ownership and commitment. He maintained that laws and regulations alone could not deliver sustainable Nigerian content unless individuals, businesses and institutions genuinely embraced the responsibility of building Nigeria’s productive capacity.
Devakumar stressed that local content must go beyond sourcing raw materials to include skills transfer, workforce development and the growth of indigenous contractors into enterprises capable of executing increasingly complex projects.
The Director of Legal Services, NCDMB, Dr. Naboth Onyesoh, called for greater coordination among regulatory institutions, stressing that investment facilitation, petroleum regulation and Nigerian content compliance must work together to advance national economic interests. He argued that inter-agency engagement should clarify statutory responsibilities, eliminate unnecessary duplication and produce practical solutions rather than become a contest over institutional superiority.
Onyesoh challenged the perception that the Oil and Gas Free Zones Authority (OGFZA) was the sole regulator within free zones, explaining that its investment-promotion responsibilities did not override the statutory mandates of other government institutions. He noted that free-zone incentives designed to attract investment and improve the ease of doing business did not exempt operators from applicable federal laws. Depending on the nature of their operations, petroleum businesses remained subject to the relevant requirements of the Nigerian Upstream Petroleum Regulatory Commission and the Nigerian Midstream and Downstream Petroleum Regulatory Authority and NCDMB.
The NCDMB legal director also highlighted the Board’s efforts to strengthen indigenous maritime capacity through the Nigerian Content Intervention Fund, which supports local companies in acquiring vessels and expanding their operations.
He disclosed that the Nigerian Content Fund was partnering with Nigeria LNG Limited on a shipyard project at Snake Island to boost domestic industrial capacity. He also commended the Nigerian Maritime Administration and Safety Agency (NIMASA) for collaborating with the Board on vessel verification and indigenous participation in maritime operations.
Onyesoh urged OGFZA and other agencies to intensify regular engagement, information sharing and joint resolution of operational challenges, noting that coordinated regulation would improve the ease of doing business, strengthen investor confidence, create jobs and ensure greater economic returns from Nigeria’s oil and gas resources.
Earlier, the Alternate Chairperson of the NCDMB/Dangote Joint Technical Committee, Dr. Ebele Oputa, described the retreat as a family meeting of key stakeholders united by a common objective: to place Nigerians at the centre of industrial development.
She acknowledged the contributions of participating government agencies and commended Devakumar for his longstanding commitment to Nigeria and investment in young Nigerians. She noted that his more than 33 years in the country and contributions to Nigerian content development had been instrumental to the collaboration.
By Tony Obiechina, Abuja
The Minister of Finance and Coordinating Minister of the Economy, Prof. Taiwo Oyedele, has unveiled the Nigeria Capital Market Master Plan 2.
0, targeting the expansion of the country’s capital market to at least $1 trillion by 2036.Oyedele announced this on Monday in Abuja while delivering a keynote address at the 2026 National Capital Market Conference, where he also formally launched the National Savings Scheme aimed at expanding financial inclusion and encouraging Nigerians to invest through regulated financial instruments.
The minister said the new master plan, covering 2026 to 2036, would strengthen the capital market’s role in financing businesses, infrastructure development, job creation and the country’s ambition to build a $1 trillion economy by 2030.
He explained that the plan was designed to mobilise domestic and international capital, expand investment opportunities, strengthen market institutions and ensure that ordinary Nigerians benefit from economic growth.
According to him, the government is targeting an increase in the capital market’s size from approximately $250 billion to between $700 billion and $750 billion by 2036, with an ambition to push it beyond $1 trillion.
Oyedele said the ultimate objective was to build a market capable of financing the economy’s long-term development needs while providing Nigerians with safe and accessible investment opportunities.
“The capital market must be part of our national economic policy. It is central to our ambition of building a $1 trillion economy by 2030,” he said.
The minister, who said he had just returned from the International Monetary Fund and World Bank Group Annual Meetings in Bangkok, Thailand, noted that mobilising private capital for job creation featured prominently in discussions involving more than 160 countries.
He said a major lesson from the international engagements was that capital moved towards markets where investors were treated fairly, policies were predictable and evidence-based decisions guided economic management.
Oyedele commended President Bola Tinubu for the economic reforms undertaken by the administration, saying the measures had contributed to the recovery of investor confidence and improved the performance of Nigeria’s capital market.
He cited the removal of the petrol subsidy, foreign exchange reforms, tax reforms and the recapitalisation of banks as measures that had helped reposition the economy and strengthen the investment environment.
According to him, the market’s equity capitalisation has risen from about N30 trillion in mid-2023 to more than N160 trillion, while pension assets have reached approximately N27.5 trillion.
He added that collective investment schemes had expanded from N1.4 trillion in 2021 to N7.7 trillion in December 2025 and N9.3 trillion by June 2026.
The minister also highlighted renewed interest from international investors, noting that the inclusion of Nigerian government bonds in a global bond index and the country’s return to an international equity benchmark represented important developments for the market.
He said the government would continue engaging international index providers, including MSCI, to improve Nigeria’s standing in global investment markets and create opportunities for increased capital inflows.
Shettima also called on market operators and regulators to sustain the momentum by protecting investors, expanding participation and ensuring that the market’s growth translated into tangible benefits for Nigerians.
He said the master plan should help businesses raise capital locally, support agricultural development, finance infrastructure and create opportunities for enterprises across the country.
The Vice-President formally declared the Nigeria Capital Market Master Plan 2.0 launched on behalf of President Tinubu.
He urged stakeholders to ensure that the plan moved beyond policy commitments to measurable outcomes, including more jobs, greater investment participation and improved access to financing for Nigerian businesses.
The conference brought together government officials, regulators, market operators, investors and development partners to discuss strategies for positioning Nigeria’s capital market as a major driver of economic growth, financial inclusion and sustainable development.
Oyedele, however, stressed that achieving these ambitions would require sustained reforms, improved market liquidity, efficient repatriation of foreign investments and stronger protection for investors.
The minister said the Capital Market Master Plan 2.0 was built around five major pillars: effective regulation, modern market infrastructure, diversified investment products, broader investor participation and stronger institutions.
Under the plan, the government intends to increase market capitalisation relative to the size of the economy, expand corporate bond issuance, deepen the pension investment market and encourage more Nigerians to participate in regulated investment schemes.
The government also plans to introduce a single investor identification number and promote investment through mobile networks and financial technology platforms to simplify access to the capital market.
Oyedele said the administration would encourage multinational companies and other eligible businesses to list on Nigerian exchanges through appropriate incentives rather than compulsory listing requirements.
He further called for the consideration of selected state-owned enterprises for listing, explaining that such a move could improve transparency, broaden public ownership and enable Nigerians to benefit from the performance of strategic national assets.
He identified the Nigerian National Petroleum Company Limited and other eligible government-linked enterprises as examples of assets whose ownership structures could be reviewed to deepen the capital market.
The minister said the plan would also promote cross-border investment and enable African businesses, including technology and artificial intelligence companies, to raise funds locally rather than relying excessively on foreign markets.
Oyedele formally launched the National Savings Scheme, describing it as an important instrument for expanding financial inclusion and helping Nigerians build wealth through regulated investments.
He said the scheme would provide accessible and affordable savings and investment opportunities for people seeking to finance education, home ownership, business ventures and retirement.
According to him, the initiative is particularly important for young Nigerians who may otherwise be exposed to unregulated cryptocurrency platforms, fraudulent investment schemes and pyramid schemes.
He observed that Nigeria had only about six million retail investors despite its large population, underscoring the need to make investment opportunities more accessible to ordinary citizens.
Earlier, the Director-General of the Securities and Exchange Commission (SEC), Dr. Emomotimi Agama, said Nigeria’s capital market had recorded significant growth but needed broader participation and more investment products to achieve its full potential.
Agama disclosed that the market’s capitalisation had crossed N100 trillion for the first time in January 2026 before reaching approximately N163 trillion in September.
He attributed the performance to economic reforms, improvements in market infrastructure and the implementation of policies aimed at strengthening investor confidence.
The SEC boss said the Investment and Securities Act 2025 had provided a stronger legal foundation for regulating the market, addressing systemic risks, overseeing digital assets and improving enforcement.
He, however, expressed concern that the market’s expansion in value had not been matched by sufficient growth in the number of participating Nigerians and businesses.
According to him, few Nigerians invest through collective investment schemes, while many businesses and infrastructure projects continue to depend on limited sources of financing.
Agama said the new master plan was developed through consultations with market operators, investors, issuers, regulators and government institutions.
He assured stakeholders that the commission would establish implementation mechanisms, assign responsibilities and regularly report progress towards the plan’s objectives.
The SEC director-general also described the National Savings Scheme as a means of helping young graduates, workers and other Nigerians save and invest for the future through professionally managed and regulated channels.
He thanked the United Kingdom government, the Foreign, Commonwealth and Development Office, and FSD Africa for their technical and financial support towards the development of the master plan and the savings initiative.Shettima: Capital market must finance national development
In a goodwill message delivered on behalf of Vice-President Kashim Shettima by the Deputy Chief of Staff to the President, Senator Ibrahim Hadejia, the Federal Government said the capital market must become a major source of financing for infrastructure, businesses and economic development.
Shettima said the expansion of the market reflected the impact of the administration’s economic reforms, including changes to the foreign exchange system, the removal of the petrol subsidy and tax reforms.
He maintained that the reforms were intended to establish a more predictable economic environment in which investors could commit long-term capital.
The Vice-President said the capital market should serve as a bridge between the savings of Nigerians and the country’s investment needs, particularly in view of the infrastructure financing gap facing the federal and state governments.
He urged state governments to work with the SEC and other relevant institutions to explore responsible financing options, including infrastructure bonds, supported by credible projects, transparency and sound fiscal management.
Shettima also called on market operators and regulators to sustain the momentum by protecting investors, expanding participation and ensuring that the market’s growth translated into tangible benefits for Nigerians.
He said the master plan should help businesses raise capital locally, support agricultural development, finance infrastructure and create opportunities for enterprises across the country.
The Vice-President formally declared the Nigeria Capital Market Master Plan 2.0 launched on behalf of President Tinubu.
He urged stakeholders to ensure that the plan moved beyond policy commitments to measurable outcomes, including more jobs, greater investment participation and improved access to financing for Nigerian businesses.
The conference brought together government officials, regulators, market operators, investors and development partners to discuss strategies for positioning Nigeria’s capital market as a major driver of economic growth, financial inclusion and sustainable development.
By Elijah Oguche, Abuja
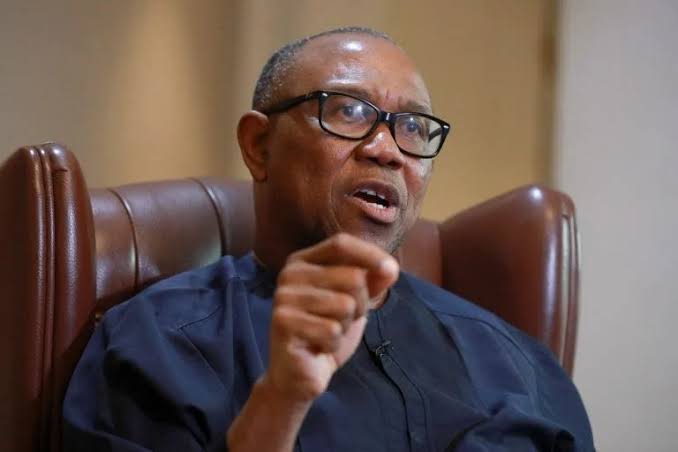
The presidential candidate of the Nigeria Democratic Congress (NDC), Peter Obi, has urged Nigerians living in the United Kingdom to stop giving money to relatives who seek financial assistance at home, saying the country needs better leadership to tackle its economic problems.
He also called on Nigerians in the diaspora to encourage their family members to vote for leaders who can improve the economy and deliver good governance.
Obi made the appeal during a town hall meeting with his supporters in Manchester, United Kingdom, on Sunday.
The former Anambra State governor blamed Nigeria’s economic hardship on poor leadership, arguing that while money sent home could help people meet their immediate needs, it would not address the root causes of poverty.
“You have people at home in Nigeria today who are begging you for money. Tell them no!” he said.
Obi also defended his record in office, particularly his handling of public funds during his tenure as governor of Anambra State.
He said he was not claiming to be perfect but maintained that his administration saved substantial public funds, adding that he had yet to see another governor save up to 10 per cent of what he claimed to have saved.
“I’m not saying I’m a saint, but I saved money. I’ve not seen one governor who has saved 10 per cent of what I saved. No governor has done it,” he said.
He urged Nigerians to begin by supporting leaders they consider less corrupt, describing it as a step towards changing the country’s political and economic fortunes.
“Let’s start with this one that is less corrupt. That’s how other countries change,” he said.
Obi further stressed that rebuilding Nigeria would require citizens to take responsibility for the country’s future rather than relying solely on individual financial support to family members.
He said his engagement with Nigerians abroad had reinforced the need for collective action to address the country’s challenges and promote better governance.
The NDC candidate also urged Nigerians to take the 2027 general election seriously, describing it as a crucial moment for the country.
He called on citizens to participate actively in the electoral process and make their votes count, stressing that leadership choices would play a major role in determining Nigeria’s future.
By Tambaya Julius, Abuja
The World Bank has urged the Federal and state governments to establish a sustainable social protection system, warning that Nigeria’s N658.9bn cash transfer programme needs wider coverage, adequate payments and regular disbursements to provide meaningful relief to vulnerable households.
As of September 2026, the Federal Government had disbursed N658.
9bn to 10.46 million poor and vulnerable households through direct cash transfers, using biometric and digital verification to identify beneficiaries and deliver payments.The bank, however, said the programme must move beyond emergency interventions to a reliable system backed by regular government funding.
The recommendation was contained in its latest Nigeria Development Update, titled ‘Beyond the Federal Purse: How Higher Revenues Shaped State Priorities’.
According to the report, the effectiveness of cash transfers depends on the number of households reached, the value of payments and how consistently beneficiaries receive them.
The bank called for dedicated budget allocations at both federal and state levels, with increased funding from domestic resources to ensure continuity and reduce dependence on temporary interventions.
It also stressed the need for stronger coordination between the two tiers of government to improve the delivery and monitoring of social assistance programmes.
The report said a predictable, adequately funded social protection system would help vulnerable Nigerians cope with economic pressures and improve household welfare.

NCDMB, Dangote Push for Sustainable Nigerian Content
ShareFrom Mike Tayese, Yenagoa The Nigerian Content Development and Monitoring Board (NCDMB) and the Dangote Group have urged a decisive...

Oyedele Unveils Capital Market Master Plan, Targets $1trn Market by 2036
ShareBy Tony Obiechina, Abuja The Minister of Finance and Coordinating Minister of the Economy, Prof. Taiwo Oyedele, has unveiled the...

OBI In London, URGES DIASPORA TO Stop FUNDING RELATIVES
ShareBy Elijah Oguche, Abuja The presidential candidate of the Nigeria Democratic Congress (NDC), Peter Obi, has urged Nigerians living in...

World Bank Tasks FG, States on Sustainable Cash Transfer Programme
ShareBy Tambaya Julius, Abuja The World Bank has urged the Federal and state governments to establish a sustainable social protection...

Former Delta Governor, Uduaghan Dies at 71
Share From Francis Sadhere, Delta Former Governor of Delta State, Dr. Emmanuel Eweta Uduaghan, has died. He was 71. Uduaghan,...

Attempted Suicide in Nigeria: Legislative Reform, Economic Hardship and the Right to Human Dignity
ShareBy Oluwaleye Adedoyin Grace Should a person who survives a suicide attempt be punished or helped? This question challenges Nigeria’s...

UBA Scores Legal Victory in N156bn Stallion Debt Case
ShareBy Tambaya Julius, Abuja United Bank for Africa (UBA) Plc has secured a favourable judgment in its N156 billion debt...

Nigeria Customs, Afreximbank Push Regional Border Modernisation
ShareBy Tambaya Julius, Abuja The Nigeria Customs Service (NCS) and the Customs administrations of Benin and Cameroon are working with...
NCDMB Heritage Energy Train 48 Nigerians in Subsea Engineering
ShareFrom Mike Tayese, Yenagoa The Nigerian Content Development and Monitoring Board (NCDMB), in partnership with Heritage Energy Operational Services Limited...
CAN: Tinubu Tasks Christians on Greater Unity
ShareBy Laide Akinboade, Abuja The first lady Senator Oluremi Tinubu, at the weekend urged all Nigerian Christians to ensure they...