BUSINESS
Cryptocurrency: We Acted in Nigerians’ Best Interest ― Emefiele

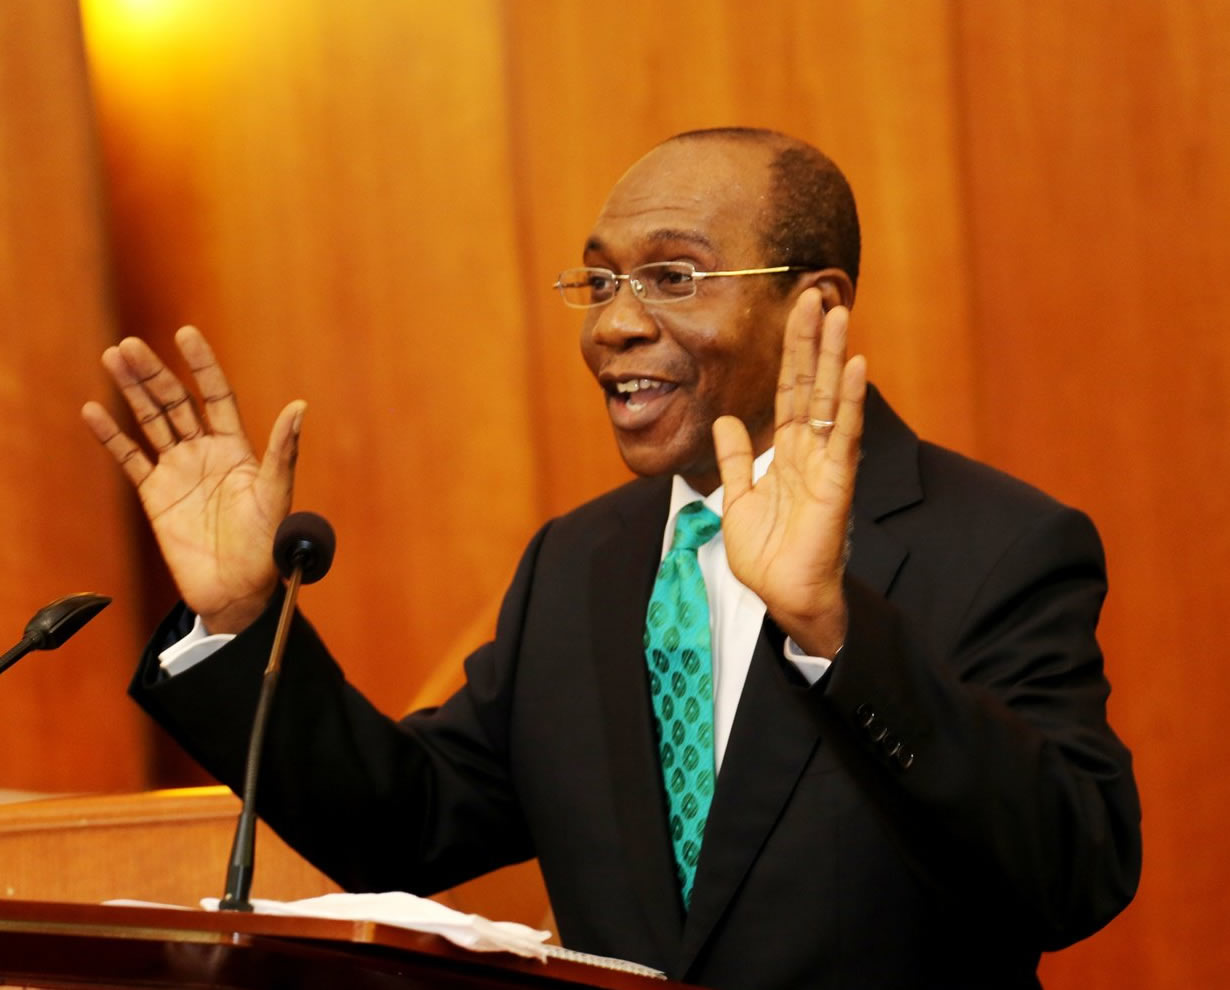
The Governor, Central Bank of Nigeria (CBN), Mr Godwin Emefiele says the Bank’s decision to prohibit deposit money banks, non-banking institutions, and other financial institutions from facilitating trading and dealings in cryptocurrency is in the best interest of Nigerian depositors and the country’s financial system.
Mr Emefiele made the declaration on Tuesday, February 23, 2021, while briefing a joint Senate Committee on Banking, Insurance and Other Financial Institutions; ICT and Cybercrime; and Capital Market, on its directive to institutions under its regulation.
Describing the operations of cryptocurrencies as dangerous and opaque, the CBN Governor said the use of cryptocurrency contravened an existing law. He said given the fact that cryptocurrencies were issued by unregulated and unlicensed entities made it contrary to the mandate of the Bank, as enshrined in the CBN Act (2007) declaring the Bank as the issuer of legal tender in Nigeria. Emefiele, who also differentiated between digital currencies, which Central Banks can issue and cryptocurrencies issued by unknown and unregulated entities, stressed that the anonymity, obscurity, and concealment of cryptocurrencies made it suitable for those who indulge in illegal activities such as money laundering, terrorism financing, purchase of small arms and light weapons and tax evasion. Citing instances of investigated criminal activities that had been linked to cryptocurrencies, he stated that the legitimacy of money and the safety of Nigeria’s financial system was central to the mandate of the CBN, even as he declared that “Cryptocurrency is not legitimate money” because it is not created or backed by any Central Bank. “Cryptocurrency has no place in our monetary system at this time and cryptocurrency transactions should not be carried out through the Nigerian banking system,” he added.
Mr Emefiele also emphasized that the Bank’s actions were not in any way, shape or form inimical to the development of FinTech or a technology-driven payment system. On the contrary, he noted that the Nigerian payment system had evolved significantly over the past decade, surpassing those of many of its counterparts in emerging, frontier and advanced economies boosted by reforms driven by the CBN. While urging that the issue of cryptocurrency be treated with caution, the CBN Governor assured that the Bank would continue its surveillance and deeper understanding of the digital space, stressing that the ultimate goal of the CBN was to do all within its regulatory powers to educate Nigerians on emerging financial risks and protect our financial system from the activities of currency speculators, money launderers, and international fraudsters. Also speaking, the Director-General of the Securities and Exchange Commission (SEC), Mr Lamido Yuguda clarified that there was no policy contradiction between the CBN directive and the pronouncements made by the SEC on the subject of cryptocurrencies in Nigeria. He explained that the SEC made its pronouncement at the time to provide regulatory certainty within the digital asset space due to the growing volume of reported flaws. Prior to the CBN directive, he said the SEC had, in 2017, cautioned the public on the risks involved in investing in digital and cryptocurrency, adding that the CBN, Nigeria Deposit Insurance Corporation (NDIC) and the SEC between 2018 and 2020 had also issued warnings on the lack of protection in investments in cryptocurrency. Yuguda further disclosed that following the CBN directive, the SEC had put on hold the admittance of all persons affected by CBN circular into its proposed regulatory incubatory framework in order to ensure that only operators that are in full compliance with extant laws and regulations are admitted into the framework for regulating digital assets.






By Tony Obiechina Abuja
Nigeria’s foreign exchange reserves rose to $58.81 billion on October 12, 2026, their highest level since November 19, 2008, when reserves stood at approximately $58.91 billion.
Data from the Central Bank of Nigeria (CBN) showed that the reserves increased from $55.
08 billion on October 9 to $58. 81 billion on October 12, representing a gain of about $3.73 billion in the latest reported movement.The latest figure extends the upward trend recorded in September and early October, strengthening Nigeria’s external reserve position amid efforts to stabilise the foreign exchange market.
Nigeria’s foreign reserves had been increasing steadily through September, moving from approximately $53.90 billion on September 1 to $54.93 billion by September 30.
The increase continued in October, with reserves reaching $54.95 billion on October 2 and $55.08 billion on October 9 before climbing to $58.81 billion on October 12.
The reserves rose from $53.90 billion on September 1 to $54.93 billion on September 30, representing an increase of $1.03 billion during the month. The reserves climbed further to $54.95 billion on October 2 and $55.08 billion on October 9 before surging to $58.81 billion on October 12.
The latest figure represents an increase of $3.73 billion between October 9 and October 12, bringing the cumulative gain since September 1 to $4.91 billion, or approximately 9.1 percent.
The latest reserve level marks a significant milestone in the country’s external reserve position, although the supplied data do not establish the specific factors behind the sharp increase between October 9 and October 12.
Nigeria’s reserves had risen by $12.76 billion year-on-year to $54.61 billion as of September 14, 2026, reflecting an improvement in the country’s external liquidity position.
Nigeria’s net foreign reserves have also risen to $46 billion. CBN Governor Olayemi Cardoso has said that stability in the foreign exchange market is helping to strengthen investor confidence.
Gross foreign reserves and net foreign reserves measure different aspects of the country’s external position, so the figures should not be treated as interchangeable.
The reserve increase comes amid changes in monetary policy and an improving economic outlook.
At its September 2026 Monetary Policy Committee meeting, the CBN reduced the Monetary Policy Rate (MPR) by 350 basis points, from 26.5 percent to 23 percent.
The committee also recalibrated the asymmetric corridor around the policy rate to +50/-300 basis points.
Meanwhile, the World Bank raised its forecast for Nigeria’s economic growth in 2026 to 4.3 percent, from 4.0 percent in 2025, and projected growth of 4.4 percent in both 2027 and 2028.

Some motorists in the Federal Capital Territory (FCT) have raised concerns over the continuous increase in the price of Premium Motor Spirit (PMS), popularly known as petrol.
The motorists said yesterday that petrol prices had continued to rise in spite of the Federal Government’s assurance to cushion the impact on consumers.
The Federal Government recently announced a 30-day discount on petrol sold by the Nigerian National Petroleum Company Limited, with public transport operators to receive priority under the arrangement.
Taiwo Oyedele, the Minister of Finance and Coordinating Minister of the Economy, said the arrangement, however, was not a return to petrol subsidy.
The minister said the government was also negotiating a ceiling of N1,350 per litre on the ex-gantry or landing cost of petrol in an effort to reduce sharp fluctuations in pump prices.
It was reported that Dangote Petroleum Refinery cut its gantry petrol price by N25 per litre to from N1,350 to N1,325.
Crude Oil Futures Price (WTI) traded at $90.41 to $90.50 per barrel for West Texas Intermediate (WTI), while international benchmark Brent crude traded near $103.33 per barrel
It showed that A.Y Shafa retail outlet increased the price from N1,370 per litre to N1,410 per litre, while MRS retail outlet increased from N1,370 per litre to N1,405 per litre.
Similarly, A.A Rano increased its pump prices from N1,380 per litre to N1,409 per litre.
A motorist, Tony Ajayi, said motorists were already grappling with rising food, transportation, household expenses, and the latest increase represented another unwelcome strain.
Ajayi said the persistent increase in fuel prices was putting growing financial pressure on families and making it increasingly difficult for many Nigerians to meet their basic needs.
Auwal Tanko, a motorist, said he bought petrol at N1,410 per litre, adding that the effect of the increase went far beyond the cost of filling his vehicle.
Tanko urged the federal government to urgently intervene by stabilising fuel prices.
Chinedu Ukadike, the National Publicity Secretary of the Independent Petroleum Marketers Association of Nigeria (IPMAN), said the Federal Government should expand access to its recently announced petroleum pricing policy.
Ukadike said the wider participation was necessary to ensure Nigerians felt the impact of an expected reduction in pump prices.
According to him, the policy’s impact will not be immediate, because the distribution of petroleum products to filling stations across the country will take time.
“Circulation of petroleum products and the quoted petroleum products is also a gradual process before it will be able to have an effect on commuters.
“The chains of distribution will be ignited by loading those products and trucks moving to their different destinations.
“The effect will not be immediately seen until within 20 days to 30 days when these products land at their destinations and in the pumps for dispensing,” he said.
He said the process involved loading the products, transporting them to various destinations and making them available for dispensing at filling stations. (NAN)

The Central Bank of Nigeria has ruled out an extension of the 1 January 2027, deadline for financial institutions to store and manage payment transaction data generated in Nigeria locally, putting pressure on banks, fintechs and payment service providers to complete their migration plans.
The disclosure was made at the CloudReady Nigeria Financial Services Roundtable, hosted in Lagos by Africa Hyperscalers Company in partnership with 100 Women in Digital Infra, Open Access Data Centres, Layer3, Nobus Cloud Services and the National Information Technology Development Agency.
Director of the CBN’s Payments System Supervision Department, Dr.
Rakiya Yusuf, reiterated the position in remarks delivered on her behalf by Assistant Director Babatunde Ajiboye at the CloudReady Nigeria Financial Services Roundtable organised by Africa Hyperscalers in Lagos. Yusuf was represented by Ajiboye, Payments Systems Supervision Division, CBN.The requirement was set out in a circular issued on 15 June 2026, directing payment service providers and other covered institutions to store and manage payment transaction data generated within Nigeria in the country. The deadline leaves affected institutions with limited time to assess their systems, review contracts with technology providers, and complete the migration of relevant data.
Yusuf said institutions must examine more than the physical location of their databases. Their compliance work should cover transaction logs, audit trails, metadata and the systems supporting payment operations.
She also warned that institutions must preserve service continuity and data integrity throughout the transition. A migration that meets the location requirement but disrupts payment services or compromises records would not adequately address the operational risks involved.
For cross-border transactions, financial institutions must ensure that records covered by the Nigerian requirement remain compliant while accounting for the needs of foreign counterparties. Institutions experiencing difficulties are expected to demonstrate the progress they have made, identify outstanding gaps and present credible plans for addressing them.
The CBN also urged financial institutions to review their agreements with cloud and technology providers to establish where data is stored, how it is processed and backed up, and whether existing arrangements can meet the new requirements.
The deadline formed part of a wider discussion about Nigeria’s push to strengthen digital sovereignty and develop local infrastructure capable of supporting sensitive financial workloads.
That would require clearer guidance on data and workload classification, resilient infrastructure, trusted service providers and coordination among regulators and industry participants, Osunrinde said.
The roundtable was intended to bring regulators, financial institutions and infrastructure providers together to discuss the practical requirements of compliance, including data residency, cybersecurity, cross-border transfers, business continuity and disaster recovery.
The discussions also highlighted the potential economic implications of the policy. More demand for locally hosted workloads could create opportunities for Nigerian cloud providers, data centre operators, cybersecurity companies and technology professionals. However, that opportunity depends on providers being able to demonstrate the security, reliability and capacity required by financial institutions.
The Chief Operating Officer of Nobus Cloud, Stephen Okoye, declared that locally developed cloud technology could support financial institutions seeking to move workloads into Nigeria while retaining the technical controls required for regulated operations.
He highlighted the role of Nigerian engineers in developing local cloud services and discussed the provider’s infrastructure, including its two availability zones. Okoye also cited the company’s compliance and assurance credentials, including ISO standards, Payment Card Industry Data Security Standard requirements, and the Nigeria Data Protection Act.
He said Nobus Cloud offered support to organisations migrating their systems, a process that can involve more than transferring information from one server to another. Institutions may need to review application dependencies, security configurations, connectivity and recovery arrangements before moving critical workloads.
Okoye also pointed to the company’s claimed 100 per cent uptime as an indication of its service reliability. For financial institutions, however, providers’ assurances must be assessed alongside their technical evidence, resilience arrangements and ability to maintain services during an outage or other disruption.
The transition is likely to require institutions to weigh local hosting options against their existing technology arrangements, particularly where applications rely on services and tools provided by international cloud platforms.
The Chief Executive Officer of Open Access Data Centres, Dr. Ayotunde Coker, said readiness for the transition would depend on the complexity and requirements of each financial institution’s workloads.
He urged institutions to assess their needs and risks before deciding what to migrate, rather than treating localisation as a straightforward relocation exercise. Financial operators need to understand the demands of their applications, the infrastructure available to support them, and the regulatory requirements that apply to their data.
Coker also highlighted the importance of local data centres, connectivity and reliable power in building a stronger digital infrastructure ecosystem. Investment in these areas will be important as demand for cloud computing and more advanced digital services, including artificial intelligence, grows.
The discussion underscored that the availability of local data centre space is only one part of readiness. Financial institutions must also consider connectivity between systems, redundancy, disaster recovery and the capacity to keep critical services running if infrastructure fails.
For institutions with applications designed around overseas cloud platforms, migration may require architectural changes and testing to ensure that systems continue to perform as expected. The process can also affect costs, depending on the complexity of the workload and the changes required.
The Nigerian Data Protection Commission also emphasised the need to protect personal data and manage the risks associated with cloud service providers.
National Commissioner and Chief Executive Officer of the commission, Dr. Vincent Olatunji, was represented at the event by Ibukunoluwa Owa. The commission’s contribution focused on the responsibilities of organisations that determine how personal data is processed and those that process it on their behalf.
Owa highlighted the need for data protection impact assessments, third-party risk assessments and appropriate data processing agreements. Institutions must understand the responsibilities of their service providers and ensure that their arrangements comply with applicable data protection requirements.
The commission’s guidance also covered breach reporting, transparent privacy policies and the need for organisations to explain how they will protect customers’ information.
Owa stressed the importance of preparing for operational disruption, including setting out appropriate remedies for possible downtime and maintaining disaster recovery plans.

2027: Group Rejects Alleged Rainbow Coalition Plot in Benue, Warns Wike, Akume Of Any Attempt To Thwart Alia’s Reelection.
ShareFrom Attah Ede, Makurdi The Benue Alliance for Good Governance and Accountability (BAGA), has raised concerns over an alleged political...

Economic Independence: CDS Empowers Veterans with Skills
ShareThe Chief of Defence Staff (CDS), Gen. Olufemi Oluyede, has reaffirmed the commitment of the Defence Headquarters (DHQ) to improving...

Beyond 23 Per Cent MPR, Should CBN Reconsider 45 Per Cent CRR to Unlock Credit?
ShareBy Blaise Udunze The last Monetary Policy Committee (MPC) meeting of the Central Bank of Nigeria (CBN) was its 307th...
Shame of a Nation: Cacophony Trails Igbokoba Naf Aircraft Crash
ShareThe tragic crash of a Nigerian Air Force (NAF) ATR-42 aircraft, registration number NAF 931, in the swampy terrain of...
CBN: Nigeria’s Foreign Reserves hit $58.81bn, Highest in 18 Years
ShareBy Tony Obiechina Abuja Nigeria’s foreign exchange reserves rose to $58.81 billion on October 12, 2026, their highest level since...

INEC Engages PWDs, Reaffirms Commitment to Inclusive Electoral Process
ShareThe Independent National Electoral Commission (INEC) has restated its commitment to an inclusive electoral process. The Resident Electoral Commissioner (REC)...

2027: Governance Won’t Take Back Seat to Campaigns –Tinubu
SharePresident Bola Tinubu has assured Nigerians that governance will not take a backseat to electioneering ahead of the 2027 presidential...


NYSC DG Task Corps Members on Safety, Networking
ShareFrom Mike Tayese, Yenagoa The Director-General of the National Youth Service Corps (NYSC), Brigadier General O. O. Nafiu, has urged...

Nigeria, EU, Euro Bank Sign €14m Grant Agreement on Fibre-Optic Infrastructure
ShareBy Tony Obiechina, Abuja The Federal Government of Nigeria, the European Union (EU) and the European Bank for Reconstruction and...

Tinubu: I Won’t Abandon Governance for 2027 Campaigns
ShareBy Tambaya Julius, Abuja President Bola Ahmed Tinubu has said he will not allow political campaigns ahead of the 2027...