NEWS
Eight died in auto crash in Imo

From Marcel Duru Owerri
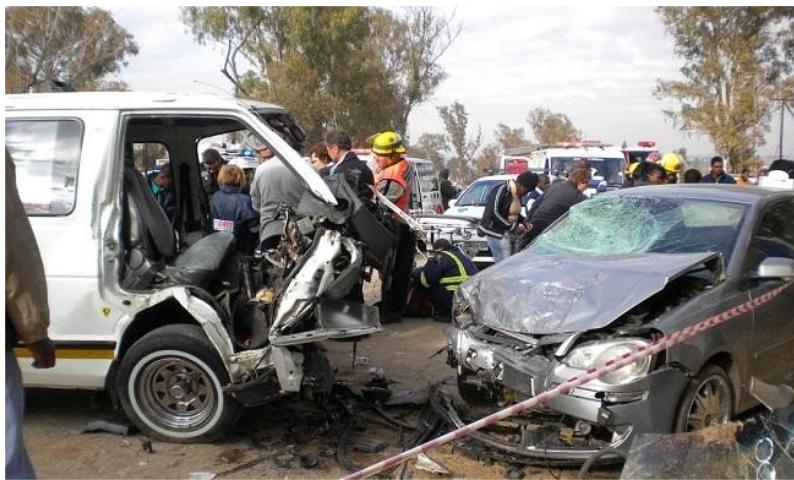
A family of eight traveling home for the new celebration has died in an auto crash at the Amanwozuzu junction in the Ikeduru Local Government Area of Imo state.
The incident which happened around 3pm on Friday has caused an anxiety in the area.
who visited the scene of the tragedy was told by eyewitnesses, passers-by and
According to Federal Road Safely Corp (FRSC)officers on rescue mission said that the father of the family who was conveying his wife and children in a sienna vehicle ran into a stationary truck carrying rod.
“The rod pierced the bodies of the victims and all of them died on the spot”
However it gathered that Policemen FRSC, and people in the area broke the vehicle to bring out the lifeless bodies of the family members.
As of the time of filing this report, policemen from the Ikeduru Local Government Area Division had deposited the bodies in a morgue.
The Divisional Police Officer in charge of the Ikeduru LGA, Lucky Ahiole, a Chief Superintendent of Police, said that the stationary truck was parked at the road side when the driver of the sienna vehicle ran into it.
The DPO said ” it is terrible. Eight died and we have taken them to a morgue. We had to break the sienna vehicle to bring out the dead”
NEWS
2027: Group Rejects Alleged Rainbow Coalition Plot in Benue, Warns Wike, Akume Of Any Attempt To Thwart Alia’s Reelection.
From Attah Ede, Makurdi
The Benue Alliance for Good Governance and Accountability (BAGA), has raised concerns over an alleged political arrangement involving prominent political figures in Benue State.
The group warned against any attempt to influence the outcome of the 2027 Benue State governorship election without the consent of voters.
The organisation alleged that it has uncovered secret political negotiations involving Wike, Akume and Ortom to unseat Governor Hyacinth Alia, insisting that Alia should be allowed to complete two terms if re-elected.
In a statement signed and made available available to newsmen in Makurdi on Wednesday by its President, Chief John Terfa, the group alleged that the Minister of the Federal Capital Territory (FCT), Nyesom Wike, was involved in discussions with the Secretary to the Government of the Federation (SGF), Senator George Akume, and former Benue State Governor Samuel Ortom over a proposed political alliance reportedly known as the “Rainbow Coalition”.
BAGA further alleged that Wike was seeking political control over five states under the Peoples Democratic Party (PDP) as part of the proposed arrangement to deliver President Bola Tinubu’s re-election in 2027, with Benue reportedly among the states being considered to hand over to Wike through the Rainbow Coalition.
The group also claimed that the alleged discussions were aimed at securing the emergence of former Attorney General of the Federation, Chief Mike Aondoakaa, as a preferred governorship candidate in Benue under the proposed coalition, despite Aondoakaa being banned from holding any political office for life by Supreme Court, for abuse of office when he was the Attorney General.
BAGA questioned why political actors from outside Benue should have a decisive influence over who governs the state, arguing that the choice of governor must remain with the electorate.
“Benue is not a political commodity to be traded behind closed doors in Abuja. The people of the state must have the final say on who governs them and the direction their state takes,” the group said.
The organisation alleged that Wike had held a series of meetings with Akume and Ortom in recent weeks to discuss the reported arrangement.
It further claimed that tensions arose during one of the alleged meetings at Akume’s residence in Abuja recently, where Wike was said to have questioned why Akume had allowed Governor Hyacinth Alia to become so politically powerful.
It was alleged that Wike demanded that Akume should make sure Governor Alia is not re-elected or declared winner in 2027 whether he wins or not and boast of having the judiciary under his control.
BAGA rejected what it described as an attempt to determine Benue’s political leadership through negotiations among powerful individuals, insisting that Governor Hyacinth Alia should be allowed to complete his constitutionally permitted tenure, if re-elected in 2027.
The group said it believed Alia’s administration was performing well in governance and development, adding that political alliances should not be used to undermine the democratic choices of the electorate.
It also criticised the record of Ortom’s administration and expressed concern about what it described as divisions within Benue’s political space arising from the influence of powerful political interests within and outside the state.
BAGA argued that any coalition seeking to influence the 2027 election should be based on transparent principles, competence, accountability and the interests of the people, rather than personal ambition or political bargaining in Abuja.
The group also challenged political actors seeking the support of President Bola Ahmed Tinubu to pursue their ambitions without attaching conditions that could compromise the democratic choices of the voters.
“Benue people are politically conscious. They will not surrender their future to a coalition of political interests formed without their consent,” the statement said.
The organisation called on voters, civil society groups and political stakeholders to remain vigilant and defend the state’s democratic rights ahead of the 2027 elections.
“Whatever colour it is given; Rainbow, PDP or otherwise, the people will reject any arrangement that threatens their collective interests and development,” BAGA said.
“Benue is not Rivers and we will not allow Wike from Rivers State to choose a governor for us in Benue State,” the group added.
According to BAGA, the central issue is whether political negotiations in Abuja will respect the right of Benue voters to determine their own leadership.
The group maintained that the state’s governorship should not be decided through private agreements among political power brokers, but through a democratic process in which the people have the final say.
The Chief of Defence Staff (CDS), Gen. Olufemi Oluyede, has reaffirmed the commitment of the Defence Headquarters (DHQ) to improving veterans’ welfare through skills acquisition and sustainable empowerment initiatives.
This was contained in a statement on Wednesday in Abuja, by the Director, Defence Information, Maj.
-Gen. Samaila Una.Oluyede gave the assurance at the opening of the 2026 Skills Acquisition Training for Veterans in the South-West geopolitical zone, held at the Headquarters, 2 Division, Nigerian Army, Ibadan.
The programme, organised by the DHQ Veterans Affairs Division, was designed to equip veterans with practical skills for economic independence and improved livelihoods.
Represented by the Director, Veterans Affairs Directorate, DHQ, Maj.-Gen. Oluwafemi Williams, the CDS said veterans’ welfare remained a priority of the Armed Forces of Nigeria.
He urged participants to maximise the opportunity by translating the skills acquired into productive ventures that would support their families and contribute to national development.
According to him, the training covers poultry farming, fisheries, snail farming, animal husbandry, livestock management and modern agricultural techniques.
Oluyede also highlighted the DHQ’s partnership with Konga/Zinox to provide serving personnel and veterans with access to subsidised purchasing options to cushion prevailing economic challenges.
He assured the veterans that the military would continue to introduce initiatives aimed at improving their quality of life in recognition of their sacrifices and service to the nation.
The programme has as its themed £Enhancing Veterans’ Capacity Building through Sustained Skill Acquisition Training for Enhanced National Development”.(NAN)
By Blaise Udunze
The last Monetary Policy Committee (MPC) meeting of the Central Bank of Nigeria (CBN) was its 307th meeting, held on September 21 and 22, 2026. The decision taken was to reduce the Monetary Policy Rate (MPR) from 26.
5 percent to 23 percent. The decision of the Committee brings back a question about how well monetary policy works in an economy that needs cheap credit.The 350-basis-point reduction happens to be a significant adjustment to the policy-rate signal. Also, keeping the Cash Reserve Requirement (CRR) at 45 percent for deposit money raises a difficult question.
Can Nigeria lower the price of money while maintaining a regulatory constraint that limits the funds banks can deploy?In this case, the question is particularly important at a time when inflation has moderated, foreign reserves have strengthened and the banking industry has completed a major recapitalisation exercise. One fact that is critical here is that if these developments point towards an improving macroeconomic environment and a stronger financial system, why should banks continue operating under such a demanding reserve requirement?
Nigeria may have taken steps to reduce the cost of borrowing without doing enough to ensure that more businesses and individuals can access loans.
At the September meeting that has now ended the MPC made a decision. The MPC chose to keep the CRR at 45 percent for deposit money banks. The MPC also kept the CRR for merchant banks at 16 percent. For non‑Treasury Single Account (non‑TSA) public‑sector deposits the CRR was set at 75 percent. Meanwhile, the CBN made another change. The CBN adjusted the Standing Facilities Corridor to be +50/-300 basis points around the MPR.
During the changes, the apex bank described the adjustment as an operational realignment. The apex bank said it aimed to strengthen monetary-policy transmission and restore the MPR’s primacy as the signal of monetary policy. In reality, this distinction matters so much to say because the decision was not necessarily a declaration that the broader monetary stance had become expansionary.
Instead, the apex bank’s move reflected an attempt to strengthen the transmission mechanism through which monetary policy decisions influence market interest rates and broader economic activity.
Meanwhile, one of the key central concerns remains whether the adjustment translates into cheaper, more accessible credit for businesses and households. The warning signs are already evident.
In its report, MPR Cut: Why Cheaper Loans May Not Come Soon, Premium Times examined the factors that could delay the transmission of the rate reduction to borrowers. The report highlighted the continued 45 per cent CRR as a constraint on banks’ capacity to expand lending and noted that existing loan agreements and differences in repricing schedules could delay the impact of lower policy rates.
This introduces an important asymmetry into the monetary-policy debate. Banks’ deposit costs may decline faster than the interest rates charged on existing loans, potentially improving their net interest margins before borrowers receive meaningful relief. In other words, a lower MPR may boost bank profitability before it shows up in the real economy.
The fact is, this is not necessarily evidence of misconduct by banks. Loan contracts have different maturities and repricing conditions, while lenders must account for credit risk, funding costs and the possibility of default. Nevertheless, it raises a legitimate policy question, which is to inquire if the purpose of recalibrating the MPR is to improve monetary-policy transmission, how quickly should the resulting benefits reach borrowers, and what prevents that from happening?
The CRR is key and central to this debate because it influences the amount of qualifying deposit liabilities banks must maintain as reserves with the CBN rather than deploy directly into loans and other assets.
A 45 per cent requirement does not mean that lending automatically falls by 45 per cent. This is to say that banks have different funding structures and CRR interacts with capital requirements, liquidity regulations and other prudential rules. In this case, it is important to clarify that the requirement imposes a substantial constraint on the deployment of qualifying deposits and can influence the economics of financial intermediation.
The CBN is therefore sending two signals simultaneously whereby the lower MPR suggests an adjustment in the direction of its policy-rate framework, and also the unchanged CRR indicates that it remains concerned about liquidity management and financial stability.
Both objectives are legitimate. The question is whether their combined effect is consistent with the level of credit expansion Nigeria needs. The debate becomes more compelling when the country’s improving external position and moderating inflation are considered.
In a separate report, Leadership questioned the continued retention of the 45 per cent CRR despite stronger foreign reserves and easing inflation. The report cited economists who argued that the CBN should reconsider the degree of liquidity restriction as macroeconomic conditions improve.
It also cited Chapel Hill Denham’s estimate that the CRR could cost the banking industry as much as N2.5 trillion annually in potential earnings. Looking at this, the figure, however, represents estimated foregone earning opportunities, not a guaranteed volume of new lending that would materialise if the reserve requirement were reduced. Nevertheless, it underscores the opportunity cost of keeping substantial funds tied up in compulsory reserves, particularly at a time when businesses are demanding more affordable credit.
The policy question is whether the benefits of that restraint continue to outweigh its potential costs to lending and investment.
Nigeria’s stronger external reserves offer another reason to reassess the balance. This is to say that higher reserves can improve external confidence and provide a buffer against foreign-exchange shocks, although they do not automatically eliminate domestic inflationary pressures. Similarly, moderating inflation creates room to reconsider the intensity of monetary restraint, but it must be made known that it does not mean that inflation risks have disappeared.
The CBN must therefore explain what conditions would justify a review of the CRR, what risks it believes still require the current level, and how it intends to balance liquidity control with productive credit expansion, as this calls for urgency.
Also, it is important to state that the issue extends beyond monetary policy to the effectiveness of banking-sector recapitalization, as the exercise raised N4.65 trillion. DataPro Limited’s assessment put the average capital adequacy ratio at 25.5 per cent and highlighted the challenge of translating stronger bank capital into more productive lending. The report also cited N2.9 trillion in loan write-offs, illustrating the importance of credit losses and asset quality.
These figures raise a fundamental question about what recapitalisation should achieve.
A stronger capital base improves a bank’s capacity to absorb losses and potentially support larger exposures. It does not guarantee that the institution will extend more credit to manufacturers, agricultural businesses, exporters or small enterprises.
Also, it is more critical that banks must still assess the probability of default, collateral quality, the enforceability of loan agreements, operating costs and the commercial prospects of borrowers. Hence, whilst these risks are high, additional capital may strengthen the balance sheet without producing a proportionate expansion in lending.
In addressing the challenges, it is key to note that the post-recapitalisation test should therefore extend beyond the capital raised and the number of banks meeting regulatory thresholds. Yes, it should also examine whether banks are expanding sustainable lending to productive sectors without compromising underwriting standards.
This is where the interaction between CRR and recapitalisation becomes particularly important. If banks have stronger capital positions but remain subject to a high reserve requirement, the CBN must consider whether its regulatory framework is sufficiently aligned with its expectations for private-sector credit growth.
The answer cannot simply be to demand more lending. The fact is that policymakers must also examine the conditions under which lending becomes commercially viable.
For small and medium-sized enterprises, this challenge is especially acute. It is very well established that businesses without substantial collateral, audited financial records or established banking relationships often face higher borrowing costs or outright rejection, even when their underlying operations are viable. Large corporations with stronger balance sheets and established relationships may negotiate more favourable terms, though they are always on banks’ bad books as defaulters.
Consequently, a lower MPR may improve conditions for some borrowers without significantly changing the credit environment for the businesses that need financing most.
The real test of monetary-policy transmission is therefore not whether the headline rate has declined, but whether the effective cost and availability of credit have improved.
It should be understood that there is also a limit to what monetary policy can achieve on its own. Nigerian manufacturers may benefit from lower working-capital costs, but expensive energy, foreign-exchange constraints, imported inputs and logistics costs remain significant determinants of production expenses. A cheaper loan cannot fully compensate for unreliable power or persistently high operating costs.
The CBN must consequently approach credit expansion as part of a wider economic framework. Monetary policy can influence the price and availability of funds, but its effectiveness depends on business conditions, credit infrastructure, the quality of borrowers and banks’ willingness to accept commercially reasonable risks.
This does not diminish the importance of the CRR. Rather, it makes the case for a more evidence-driven review of its application.
Instead, it supports an evidence-based review of how the policy is applied.
Rather than removing the requirement all at once, the CBN might look at a gradual adjustment. This could be linked to inflation expectations, how much liquidity is in the banking system, stability in foreign exchange markets and whether credit growth’s strong and well-managed.
The CBN could also explore incentives for lending to sectors. These incentives must be carefully built, with clear eligibility rules and strong monitoring to make sure they work as intended.
Such an approach would need safeguards as this would help ensure that the extra money flowing into the banking system goes towards productive investments rather than speculation or activities that do little to grow the economy. Meanwhile, there is a need to clarify here that reducing CRR does not guarantee that banks will lend the released funds to businesses.
They could instead favour government securities, foreign-exchange-related transactions or other assets offering more attractive risk-adjusted returns as this has continued to be a repeated pattern in the system.
The objective must therefore be to improve productive credit allocation, not simply increase liquidity.
The CBN should establish transparent conditions for reviewing the 45 per cent CRR and publish evidence showing whether its policy decisions are improving credit access. Part of the measures must involve evidence that should include effective lending rates, loan applications and approvals, actual disbursements, private-sector credit growth, and financing to small businesses, manufacturing, agriculture and other productive sectors.
The functionality of how interbank rates and Treasury bill yields behave should also be watched because that tells us how the new MPR framework is affecting financial‑market conditions. Stakeholders must look at these indicators together with the real borrowing costs that businesses and households experience.
If the policy‑rate signal improves but the effective lending rates stay high and the credit approvals do not grow, the CBN must find out why the transmission is failing. Is the issue the cost of funds, the CRR, the credit risk, inadequate collateral, weak competition or a mix of these reasons?
The answers should determine the policy response rather than an assumption that any single instrument can resolve the problem.
This is also the appropriate way to judge recapitalisation. In reality, banks should not be compelled to extend unsustainable loans merely to meet a credit-growth target. In situations like this, a stronger banking system should be capable of demonstrating how it supports productive economic activity, which is key, particularly where viable businesses face financing constraints.
Nigeria needs a monetary policy that controls inflation while allowing banks to lend to businesses that can grow the economy. The CBN is right to be concerned about inflation, exchange-rate pressures and financial stability.
But monetary instruments must be continually assessed against changing economic conditions. Clearly, a rule that requires banks to keep an amount of money on hand that is reasonable, in one situation should not stop being checked when the big economic conditions change.
The 23 percent MPR and 45 percent CRR can exist together inside a monetary-policy plan. The real question is whether the combined result helps the CBNs goals, for stability, investment and term economic growth.
If the MPR falls while the cost and availability of credit remain largely unchanged, Nigeria will have adjusted the price signal of monetary policy without adequately addressing the constraints on financial intermediation.
Following the developments thus far, the next phase must therefore go beyond announcing lower rates. Yes, in truth, it must demonstrate that stronger bank capital, improving macroeconomic conditions and better monetary-policy transmission are translating into sustainable financing for productive businesses.
Ultimately, this must be made clearly known that the success of the 23 percent MPR will not be determined by the announcement itself. The real truth is that success will depend on whether the Nigerian entrepreneur, manufacturer, farmer and small‑business owner can obtain credit that’s affordable, easy to reach and lasting.
Until that happens, the question about the 45 percent CRR will not go away. Does monetary policy set up conditions that help growth or does the liquidity restriction still keep money from turning into credit that people can use or access?
Blaise, a journalist and PR professional, writes from Lagos and can be reached via: blaise.udunze@gmail.com

2027: Group Rejects Alleged Rainbow Coalition Plot in Benue, Warns Wike, Akume Of Any Attempt To Thwart Alia’s Reelection.
ShareFrom Attah Ede, Makurdi The Benue Alliance for Good Governance and Accountability (BAGA), has raised concerns over an alleged political...

Economic Independence: CDS Empowers Veterans with Skills
ShareThe Chief of Defence Staff (CDS), Gen. Olufemi Oluyede, has reaffirmed the commitment of the Defence Headquarters (DHQ) to improving...

Beyond 23 Per Cent MPR, Should CBN Reconsider 45 Per Cent CRR to Unlock Credit?
ShareBy Blaise Udunze The last Monetary Policy Committee (MPC) meeting of the Central Bank of Nigeria (CBN) was its 307th...
Shame of a Nation: Cacophony Trails Igbokoba Naf Aircraft Crash
ShareThe tragic crash of a Nigerian Air Force (NAF) ATR-42 aircraft, registration number NAF 931, in the swampy terrain of...
CBN: Nigeria’s Foreign Reserves hit $58.81bn, Highest in 18 Years
ShareBy Tony Obiechina Abuja Nigeria’s foreign exchange reserves rose to $58.81 billion on October 12, 2026, their highest level since...

INEC Engages PWDs, Reaffirms Commitment to Inclusive Electoral Process
ShareThe Independent National Electoral Commission (INEC) has restated its commitment to an inclusive electoral process. The Resident Electoral Commissioner (REC)...

2027: Governance Won’t Take Back Seat to Campaigns –Tinubu
SharePresident Bola Tinubu has assured Nigerians that governance will not take a backseat to electioneering ahead of the 2027 presidential...


NYSC DG Task Corps Members on Safety, Networking
ShareFrom Mike Tayese, Yenagoa The Director-General of the National Youth Service Corps (NYSC), Brigadier General O. O. Nafiu, has urged...

Nigeria, EU, Euro Bank Sign €14m Grant Agreement on Fibre-Optic Infrastructure
ShareBy Tony Obiechina, Abuja The Federal Government of Nigeria, the European Union (EU) and the European Bank for Reconstruction and...

Tinubu: I Won’t Abandon Governance for 2027 Campaigns
ShareBy Tambaya Julius, Abuja President Bola Ahmed Tinubu has said he will not allow political campaigns ahead of the 2027...