NEWS
SEC Mobilises Capital Market Community to Support Tinubu’s $6trn economy

By Tony Obiechina, Abuja
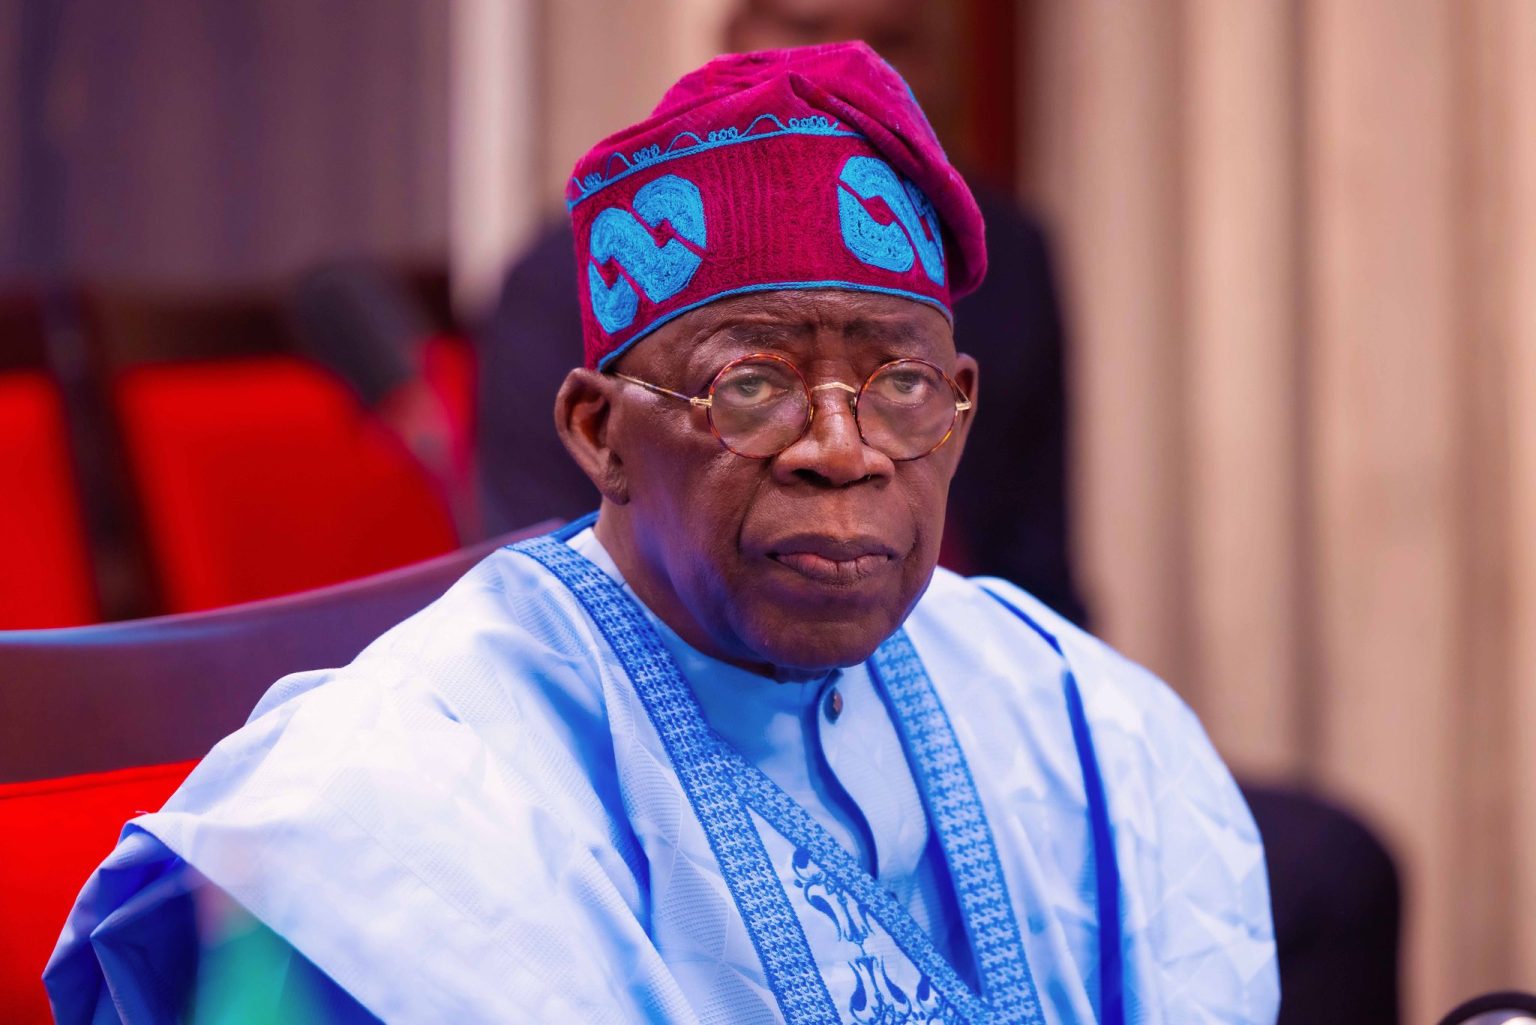
The Federal Government’s aspiration to grow the nation’s economy by a trillion dollars and $3 trillion within a decade respectively has found expression and allies in the nation’s capital market community.
President Bola Ahmed Tinubu had told the business community who gathered at the Nigerian Economic Summit in October that Nigeria’s economy can grow by US$1.
0 trillion and US$3.0 trillion is possible by 2026 and within 10 years respectively. He added that financing the country’s US $3.0 trillion national infrastructure stock can be achieved in 10 years and not 300 years.According to him, “Building megacities in every geopolitical zone of the size and scale of Lagos, must not take us another six decades. We can do it in one decade. A fully networked and connected Nigeria by rail, gas, fiber optics and road network can be constructed in less than 20 years.”
While some people may consider it as a political statement, the Director-General of the Securities & Exchange Commission Mr. Lamido Yuguda who doubles as Chairman of the Capital Market Committee is confident and optimistic that it can be achieved by unlocking the full potentials of the capital market and aligning it with the Renewed Hope Agenda of the President and Commander-in-Chief of the Armed Forces of the Federal Republic of Nigeria, His Excellency Chief Ahmed Bola Tinubu administration.
This he said on Thursday 16th November 2023 at The third 2023 Capital Market Committee (CMC) meeting held at the Federal Palace Hotel, Lagos.
Present were major key decision makers of the capital market and key industry players whom he had invited for the occasion.
Among these were representatives from the National Assembly, the Federal Ministry of Finance, Federal Inland Revenue Service, Central Bank of Nigeria (CBN), Bureau of Public Enterprise (BPE), Asset Management Corporation (AMCON), National Pension Commission (PENCOM), Ministry of Trade and Investment,
Nigeria Investment Promotion Council (NIPC); Representatives of Trade Groups; Chairman of the Senate Committee on Capital Market; Chairman of the House Committee on Capital Market and Institutions; Chief Executive Officers of Nigerian Exchange; Abuja Securities and Commodity Exchange; Central Securities Clearing System (CSCS); and Chartered Institute of Chartered Brokers (CIS); Asset Management Corporation of Nigeria (AMCON); Corporate Affairs Commission (CAC); Debt Management Office (DMO); Central Bank of Nigeria (CBN); Federal Ministry of Finance (FMF); Federal Mortgage Bank; Federal Inland Revenue Service (FIRS); Nigerian Deposit Insurance Corporation (NDIC); Investment and Securities Tribunal (IST); Nigerian Investment Promotion Council (NIPC);
National Insurance Commission (NAICOM); National Pension Commission (PENCOM).
There was no better and appropriate place to consider an effective implementation of such a big ambition. The capital market is the only platform specifically structured to bridge medium-to-long term financial resource gaps for an economy, distinct from the money market segment which is structured for providing short tenured funds of not more than 12 months.
Lagos as mentioned by Mr. President is not a misstatement. It remains the most industrialized state in Nigeria and sub-Saharan Africa. It resorted severally to the capital market to source its funding through issuance of state bonds to finance infrastructure development projects, made possible with supporting disciplined legal processes such as enactment of new Bond Law, establishment of Irrevocable Standing Payment Orders which guaranteed payment to bondholders; the use of a Consolidated Debt Service Account (CDSA) and Sinking Fund for the benefit of bondholders.
At the meeting, Chairman of the Senate Committee on Capital Market, Distinguished Senator Osita B. Izunaso; his Deputy, Distinguished Senator Peter N. Jiya as well as Chairman of the House Committee on Capital Market and Institutions, Hon Solomon T. Bob; and his deputy Hon. Dr. Mukhtar Umar Zakari was unanimous in pledging the readiness of their committees to contribute towards facilitating the development of an ecosystem that would ensure efficient access to capital formation through regular and effective consultation, cooperation and information exchange.
Senator Osita B. Іzunaso, informed the Committee that legislative initiatives such as the repeal of the Investments and Securities Act (ISA) 2007, has already passed 1st and 2nd Reading at the House of Representatives and also 1st reading at the Senate. His immediate assignment would be to help in expediting the process and aiming for submission to the President for assent by the first quarter of 2024.
He then reaffirmed that the envisioned one trillion-dollar economy can be realized through effective collaboration and productive actions in the market.
The various technical committees’ quarterly reports as presented confirmed the resilience of the nation’s capital market and its positive achievements in spite of the global economic and political turmoil, uncertainties and tension, less than expected growth projections and economic, business activities.
Some major achievements paraded include the about-to-be launched revamped e-Dividend portal, a collaborative effort of the e-Dividend Mandate Technical Committee, the Institute of Capital Market Registrars (ICMR) and Nigeria Interbank Settlement System Plc (NIBSS).
The launch of the revamped e-Dividend portal will bring a host of benefits to investors, further minimizing infractions by registrars. The e-Dividend portal is part of the E-Dividend Management System (E-DMMS) which has been seen as a breakthrough in solving the problems of unclaimed dividends in the Nigerian Capital Market, now risen to about #190 billion.
Since its launch on November 23, 2015, it has provided investors with direct access to their dividends while the endemic problem of stale dividend warrants has been eliminated. Furthermore, travelling from one place to another to deposit dividend warrants has been eliminated.
The revamped portal will provide more comprehensive and updated data from 18 out of 19 Registrars.
The dynamics of the non-interest capital market is blossoming as more and more investors enter to participate in successive issuances of Sukuk.
The issuance of the 6th FGN Sukuk by the Debt Management Office (DMO) witnessed a remarkable success in subscription level of 435 percent. There was also a flotation of an additional Shariah-compliant fixed Income fund. Plans are being finalized to expand awareness and engagement of various stakeholders to explore the development of Shariah-compliant Liquidity instruments for the commodities market and more efforts are being made towards the creation of short-term Sukuk with DMO.
Plans are also underway to secure approval of certain standards and the adoption of additional commodity standards that are already sanctioned by the African Organization for Standardization (ARSO)
De-risking the commodities’ ecosystem is also being envisaged to introduce insurance products suitable for the needs of commodities producers and traders.
From the Nigerian Exchange (NGX) there was a +36.67 percent rise in performance of the All Share Index underscoring the market’s resilience in spite of a slow-down in the participation of foreign investors. Improved sentiments among domestic retail investors and attractive yield of some stocks were some of the major contributors to the improved performance.
FMDQ emerged from the 3rd Quarter with a number of good news, including its recent launch of the Nigerian Housing Strategy Blueprint (NHSB) to the Federal Ministry of Housing and Urban Development. It was also reported that all stages of the FMDQ Derivatives Market Development Project have been successfully executed, while necessary regulatory approvals have been secured for additional derivatives products.
A 23 percent growth in the average daily clearing and settlement value brought the Central Clearing and Settlement value to around #10.7 billion in the third quarter of 2023 and a 60 percent increase on a year-on-year basis is good news. It was also noted that monthly investor KYC recorded 8,572 Accounts being updated, amounting to 31 percent increase when compared to Q2, 2023 record.
Capacity building for the Nigerian Capital Market will soon receive a boost , courtesy of the Nigerian Capital Market Institute (NCMI) which has turned around its faculties towards achieving academic excellence and injecting industry experience. Its Board of Directors has approved the introduction of seven (7) new specialized programs on Investment Banking, Compliance, Islamic Finance, Investment Management, Corporate Governance, Commodities Market and Fintech.
The appointment of Mr Anthony Atuche as Managing Director and Chief Executive Officer of the Nigerian Commodities Exchange and the rebranding of the Agency are welcome developments for revamping the agency and refocusing it for optimum performance. For several years, the organization has been operating under a Transition Management Team. It has now been rebranded as an institution with a private sector outlook but with public sector ownership.
In order to launch out fully towards deploying all its arsenals to support the president’s ambition, more effort must be expanded in the following areas: Digitization; Market modernization; Further collaboration with local and international bodies, e.g. the International Organization of Securities Commissions (IOSCO), African Stock Exchange Association (ASEA), multilateral Agencies such as the World Bank; creating more awareness of the benefits of the capital market, non existence of the Non-Interest Pension Funds; establishment of commodities market for Non-Interest instruments; expanding the current limited pool of investment grade potential for corporate Sukuk issuers within the Capital Market, increase the patronage of foreign investors which market has remained skewed domestic investors, the recent reclassification of Nigerian securities indices by FTSE-Russel and MSCI, due to foreign exchange liquidity challenges and its effects on investor confidence.
The Securities & Exchange Commission has noted these challenges and are taking drastic measures to overcome them with new strategies, taking into consideration the detailed and revised Nigerian Capital Market Master Plan 2015–2025 which remains a blueprint for positioning the capital market for efficiency and international competitiveness.
From Mike Tayese, Yenagoa
Bayelsa State Government over the weekend said the total salary-related items to civil servants in the state was N13.2 billion as at the month of September 2026.
The salary related-items, which cover 65,411 civil servants includes, N8 billion; salary arrears, 208 million; political appointees, N2 billion; gratuity, N200 million; pension arrears, N200 million; grants to tertiary institutions, N2 billion; support to primary school teachers, N251 million; corps members, N73 million and minimum wage arrears, N50 million.
“This brings total salary-related items to 13.2 billion” the state government said.Given the income and expenditures for the month of August and September 2026, the Technical Adviser to the governor on Treasury and Account Timinipre Seipulo said, it received a total of N183.28 billion in revenue from the Federation Account Allocation Committee (FAAC) and other sources in August and September 2026, while reaffirming its commitment to completing ongoing infrastructure projects and improving workers’ welfare.
Presenting the income and expenditure for the two months, Timipre Seipulo said, Bayelsa received a gross FAAC inflow of N79.20 billion in August, comprising N12.71 billion from statutory allocation, N50.14 billion from derivation revenue and N16.36 billion from Value Added Tax (VAT),after deductions at source of N993 million, the state’s net FAAC receipt stood at N78.21 billion.
The state also recorded additional receipts from internally generated revenue, infrastructure development funds, excess crude refunds and other sources, bringing its total receipts for August to approximately N99.21 billion.
For September, Seipolu said the state received a gross FAAC allocation of N56.60 billion, comprising N8.6 billion in statutory allocation, N39.32 billion from derivation and N8.7 billion from VAT.
“He explained that after deductions, the net FAAC inflow stood at approximately N55.05 billion, while additional revenue from internally generated revenue, infrastructure development funds, natural resources development, the State Employment and Expenditure for Results (SEEFOR) programme and other sources increased the state’s total receipts to about N84.07 billion.”
The presentation showed that the government spent N7.26 billion on recurrent expenditure and N28.36 billion on capital projects in September, bringing the combined expenditure to N35.62 billion.
“Seipolu further disclosed that the state had a closing balance of approximately N59.04 billion at the end of september,however, he explained that between the end of september and october 19, before the next FAAC allocation was received, the government had spent about N18.9 billion on capital projects and N4.9 billion on recurrent obligations.”
He said the balance consequently stood at approximately N35.5 billion as of October 19, with N24 billion retained in the capital projects account to support ongoing infrastructure development.
According to him, the funds were not idle resources but were being deployed to finance government obligations and ongoing projects pending subsequent FAAC allocations,on workers’ welfare, the government clarified that different categories of public servants operated under distinct salary structures and allowance arrangements.
It explained that doctors, nurses, investigators, civil servants, university employees and fire service personnel had different remuneration structures, making it inappropriate to calculate the state’s wage bill using a uniform salary estimate.
The government added that professionals such as doctors, nurses and investigators received special allowances in addition to their regular salaries to recognise the peculiar demands of their duties.
It also announced that approved special allowances for workers in tertiary institutions would commence in October, with the government committing to pay outstanding arrears dating back to January 2026.
“The allowances for tertiary institution workers are expected to increase the monthly wage bill by more than N900 million, while the additional peculiar allowances for other public servants are projected to raise monthly salary expenditure by approximately N2 billion.”
The government said the two adjustments would increase the state’s monthly wage bill by about N3 billion, excluding the outstanding arrears,it maintained that the financial disclosure was part of its commitment to transparency and accountability.
At end of September 2026, the state recorded surplus of N28.9b.
Speaking earlier,the commissioner for Information, Orientation and Strategy, Ebiuwou Koku-Obiyai, said
the present administration deliberately sustained the transparency as a covenant with the people to “govern openly, to account truthfully and to listen attentively. Transparency is not an event. It is our own culture”.
“Every project we commissioned, every kobo we spend, and every policy we implement, we bring to the members of the public through you, members of the Fort Estate of the Realm, to the people. After all, as a government, we are not
“Koku-Obiyai maintained that ongoing projects were progressing according to schedule, stressing that the government had continued to meet its financial obligations to contractors to ensure their timely completion.”
“She listed the nine-storey State Secretariat building, the rehabilitation of the Light Floor project and the Lagos road project among the major infrastructure projects making progress,
according to her, an inspection visit conducted by the commissioner for works and other government officials confirmed that the Lagos road project had reached an advanced stage of implementation.”
She described the reports alleging the collapse of major projects as misleading, insisting that the government remained committed to delivering its development agenda.
By David Torough, Abuja
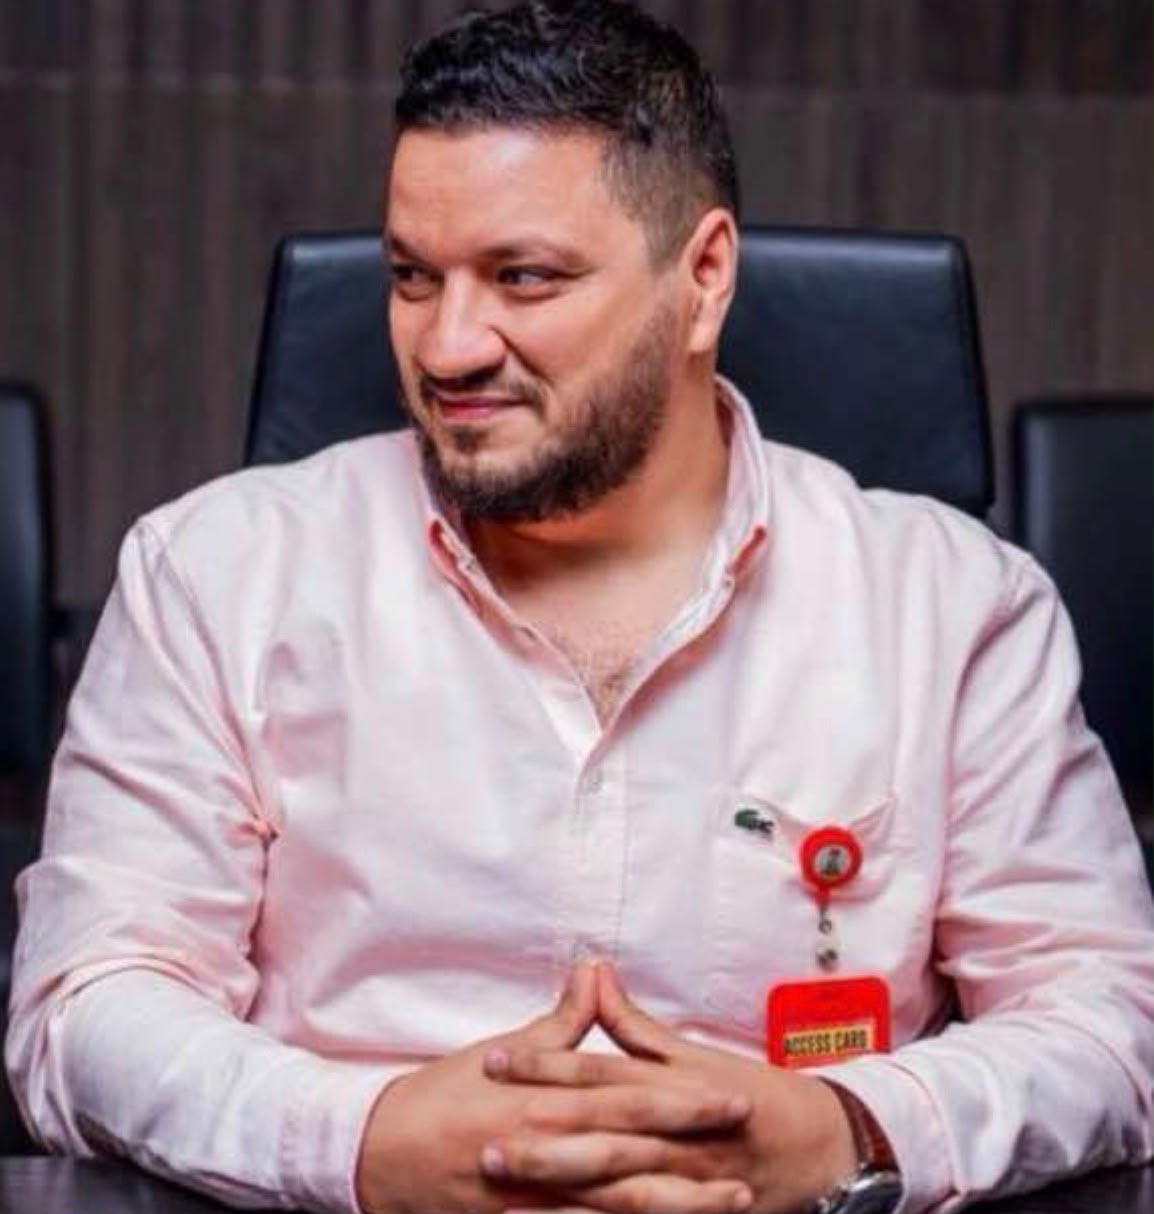
Aba Commercial Smart City has celebrated its Chief Operating Officer (COO), Engr. Mazen Kalassina, on his 39th birthday, recognising his contributions to engineering, infrastructure development, entrepreneurship, and artificial intelligence (AI) innovation.
The organisation described Kalassina as a distinguished civil engineer and technology innovator whose professional journey reflects a commitment to bridging traditional engineering practices with emerging digital technologies.
With more than 15 years of experience in engineering and infrastructure development, Kalassina has built a reputation for strategic leadership, innovation, and developing practical solutions to infrastructure challenges.
As the founder of Infrax Tech, he is leading the development of Infranalyze AI, an artificial intelligence-powered civil engineering decision-support and design platform.
The technology is designed to support critical engineering processes, including infrastructure planning, terrain analysis, road design, earthwork calculations, and drainage planning.
His growing involvement in artificial intelligence research and innovation has also attracted recognition, with his work associated with consideration for the Artificial Intelligence Research and Innovation category at the Association for the Advancement of Artificial Intelligence (AAAI). However, any final award or selection outcome remains subject to official confirmation.
At Aba Commercial Smart City, where he serves as COO, Kalassina brings his engineering background, operational expertise, and strategic vision to the development of a modern commercial city focused on economic growth, connectivity, and sustainable development.
The management of Aba Commercial Smart City, in its birthday message, commended his dedication, leadership, and commitment to excellence, describing his contributions as valuable to the organisation’s development ambitions.
The organisation also expressed optimism that his new year would usher in greater professional accomplishments, groundbreaking innovations, stronger partnerships, and lasting contributions to Nigeria’s infrastructure and technology sectors.
As he marks his 39th birthday, Aba Commercial Smart City celebrates not only his personal milestone but also his continued commitment to using engineering expertise and technological innovation to advance infrastructure development and shape the future.
Happy 39th Birthday to Engr. Mazen Kalassina!
NEWS
Rebuilding Public Trust in Government Borrowing: The Case for Scaling Up Sukuk Financing in Nigeria
By Uche Joe Uwaleke
The recent request by President Bola Tinubu to the National Assembly for approval to raise $20.52 billion and €1.045 billion in fresh external loans has once again brought Nigeria’s growing public debt burden into sharp focus.
Although the President has justified the proposed borrowing on the grounds of the country’s enormous infrastructure deficit and the need to finance critical projects across various sectors of the economy, the announcement has understandably generated considerable concern among Nigerians.These concerns cannot be dismissed as mere opposition to government borrowing.
They must be viewed against the background of Nigeria’s debt accumulation over the past decade, the relatively limited visible impact of such borrowing on infrastructure development and the growing proportion of government revenue devoted to servicing existing debt.
The fundamental question Nigerians are asking is whether borrowed funds are being efficiently deployed, transparently managed and translated into tangible developmental outcomes.
Nigeria’s public debt statistics provide sufficient grounds for this concern.
As at June 30, 2026, the country’s total public debt stood at ₦166.79 trillion, comprising domestic debt of ₦91.59 trillion, representing 54.91 per cent, and external debt of ₦75.20 trillion, equivalent to $54.52 billion, representing 45.09 per cent of the total.
This represents a phenomenal increase from the ₦11.24 trillion public debt stock recorded in December 2014.
While part of this increase reflects naira devaluation, and the securitization of previously accumulated obligations, the scale of the expansion over a relatively short period raises legitimate questions about debt sustainability and the developmental returns on borrowed resources.
More importantly, Nigeria’s debt challenge should not be assessed exclusively through the conventional debt-to-GDP ratio.
Although this ratio may appear moderate by international standards, the more immediate fiscal constraint is the country’s capacity to generate sufficient revenue to service its obligations.
Debt service has, in recent years, consumed an exceptionally high proportion of government revenue, averaging in excess of 70 per cent over the period under consideration.
This leaves progressively less fiscal space for infrastructure, education, healthcare and other essential public services.
The composition of Nigeria’s debt portfolio also raises important questions about the extent to which borrowing has been linked to productive investment.
The Federal Government’s domestic debt stock outstanding by instruments as at June 30, 2026, stood at ₦86.99 trillion.
Of this amount, discretionary FGN Bonds accounted for ₦64.84 trillion, representing 74.53 per cent of the total, including ₦22.11 trillion in securitized Ways and Means advances.
By comparison, FGN Sukuk outstanding amounted to only ₦1.19 trillion, representing 1.37 per cent, while FGN Green Bonds accounted for a mere ₦47.36 billion, or 0.05 per cent.
The overwhelming dominance of conventional government securities, particularly instruments that are not necessarily tied to specific infrastructure projects, contrasts sharply with the relatively insignificant contribution of instruments specifically designed to finance identifiable developmental investments.
This is not to suggest that all conventional government bonds are unproductive or that their proceeds cannot finance capital expenditure.
Rather, it highlights the need to rebalance the debt portfolio towards financing instruments that establish a clearer connection between borrowed funds and identifiable development projects.
The external debt portfolio presents a related challenge.
Of Nigeria’s external debt stock of $54.52 billion, Eurobonds account for a significant proportion, amounting to about $18.55 billion. Although Eurobonds provide access to international capital markets and can help diversify the sources of government financing, they are generally not structured around specific infrastructure assets or projects.
Their proceeds may be applied to broad budgetary purposes, depending on the terms of the issuance and the government’s stated financing objectives.
Furthermore, Nigeria faces substantial future Eurobond repayment obligations.
The outstanding repayment schedule includes a $1.5 billion bullet repayment falling due in November 2027, followed by significant annual maturities from 2028 through 2034, before repayments resume in 2036 and continue into 2051.
These obligations underscore the importance of carefully managing the country’s refinancing and foreign exchange risks.
They also reinforce the need to reconsider the composition and structure of future external borrowing rather than continually relying on conventional debt instruments without sufficient attention to the developmental use of their proceeds.
It is against this background that greater consideration should be given to Sukuk as an alternative and complementary instrument for financing Nigeria’s infrastructure requirements.
Properly structured Sukuk provide an opportunity to link the raising of funds to clearly identified assets and development projects, thereby creating a financing framework in which the purpose of borrowing is more transparent and the application of proceeds can be more effectively monitored.
This makes Sukuk particularly relevant to a country seeking to address a significant infrastructure deficit while simultaneously rebuilding public confidence in government borrowing.
Nigeria is not starting from scratch in this regard.
The Federal Government introduced its Sovereign Sukuk programme in 2017, and successive issuances have been deployed principally towards the construction and rehabilitation of federal roads across the six geopolitical zones and the Federal Capital Territory.
The programme has demonstrated that Sukuk can mobilize substantial domestic financial resources for identifiable infrastructure projects.
At the subnational level, Osun State issued an ₦11.4 billion Sukuk in 2013 to finance the construction of 26 schools, while Lagos State subsequently accessed the Sukuk market to finance road infrastructure.
These experiences demonstrate that Sukuk is a financing instrument that can be deployed by both federal and state governments, irrespective of the religious composition of their populations.
The results achieved through the Federal Government’s existing Sukuk programme provide an important basis for scaling up its use.
The roads financed through successive issuances demonstrate the practical connection that can be established between public borrowing and physical infrastructure delivery.
However, with outstanding Federal Government Sukuk accounting for only about 1.37 per cent of the domestic debt portfolio, its current scale remains too small to make a transformational impact on the country’s infrastructure deficit.
An important consideration is that Sukuk financing is not limited to the domestic capital market.
Both domestic and foreign loans can be sourced through Sukuk structures.
The Federal Government could therefore explore international sovereign Sukuk denominated in US dollars, euros or other suitable currencies to mobilize long-term financing from international banks, conventional institutional investors, sovereign wealth funds, pension funds and other global investment institutions.
The proposed external borrowing of $20.52 billion and €1.045 billion offers an opportunity to examine whether a significant proportion of the financing requirements could be raised through international sovereign Sukuk rather than relying exclusively on conventional external loans.
Different Sukuk structures could be deployed depending on the nature of the projects.
Al-Ijarah Sukuk could finance existing or identifiable infrastructure assets through leasing arrangements, while Al-Istisna Sukuk could be used to finance the construction of new infrastructure such as roads, bridges, and power facilities.
Al-Musharakah could support commercially viable infrastructure investments involving partnerships between government and private investors.
The flexibility of these structures makes it possible to develop a diversified infrastructure financing programme rather than rely on a single financing model.
A carefully designed international sovereign Sukuk programme could also attract investors who might otherwise not participate in Nigeria’s conventional Eurobond issuances, thereby broadening the country’s financing options and investor base.
More importantly, the appeal of Sukuk lies in its potential to strengthen transparency and accountability in the utilization of public borrowing.
One of the principal reasons for public scepticism towards government borrowing is the perceived disconnect between the amounts borrowed and the infrastructure outcomes delivered.
Nigerians are increasingly concerned that governments accumulate enormous debt obligations without providing sufficient information about the projects financed, the amounts disbursed, the physical progress achieved and the economic returns generated.
This perception has weakened public confidence in borrowing as an instrument of development.
Sukuk can help change this narrative, provided that its project-linked features are supported by effective institutional and contractual safeguards.
Each issuance should identify the projects to be financed, their locations, approved costs, implementing agencies and expected completion periods.
The proceeds should be paid into dedicated, ring-fenced accounts and released only against verified project expenditure.
Independent technical auditors should certify work completed, while periodic public disclosures should provide information on funds raised, amounts disbursed, outstanding balances and actual physical progress.
Where appropriate, special purpose vehicles should be established to administer the transactions and provide clear reporting and governance arrangements.
This approach is also consistent with the spirit and objectives of the Fiscal Responsibility Act 2007.
The Act establishes important principles for responsible fiscal management, including the requirement that borrowing be undertaken for capital expenditure and human development, subject to the applicable statutory conditions.
Section 44 specifically provides that government borrowing should be applied only to capital expenditure and human development, while the Act also provides for transparency, accountability and prudent management of public resources.
Indeed, Sukuk can provide a practical financing mechanism for advancing these objectives by establishing a more visible connection between the resources mobilized and the capital projects for which they are intended.
However, Sukuk should complement, rather than substitute for, full compliance with the Act.
The fact that a loan is raised through Sukuk does not automatically establish that the borrowing satisfies the statutory requirements.
Proper project appraisal, legislative scrutiny, debt sustainability analysis, procurement compliance and expenditure monitoring remain indispensable.
There is also a compelling case for state governments to embrace Sukuk more actively.
Given the enormous infrastructure requirements at the subnational level, state governments should explore domestic Sukuk issuances to finance roads, schools, water projects, markets and other essential public infrastructure.
States with viable revenue-generating assets or identifiable public infrastructure projects could develop their own Sukuk programmes, subject to the necessary legal approvals, credit assessments and investor requirements.
This would deepen the domestic capital market, provide institutional investors with additional investment opportunities and reduce exclusive dependence on conventional bank loans and government bonds.
It would also encourage greater discipline in project selection, preparation and implementation, since successful Sukuk issuance requires clearly defined underlying transactions and credible financing arrangements.
By and large, the issue is not whether borrowing by the government should stop altogether.
A country with enormous infrastructure deficits and development aspirations cannot reasonably expect to finance all its requirements from current revenue.
Borrowing, when properly structured and prudently managed, can be an important instrument of economic transformation.
The more fundamental issue is the quality, purpose, structure and accountability of the borrowing.
Nigeria must move away from a debt management approach that places disproportionate emphasis on how much money can be raised towards one that gives equal, if not greater, attention to what the money will finance, how it will be spent and what measurable economic and social benefits will accrue to citizens.
The proposed $20.52 billion and €1.045 billion external borrowing should therefore provide an opportunity for a fundamental rethink of the country’s financing strategy.
Rather than a complete resort to conventional loans, the Federal Government should undertake a serious assessment of the proportion of its proposed infrastructure financing that can be mobilized through international Sukuk.
The National Assembly, in considering the proposed borrowing plan, should also request a comparative assessment of conventional external loans and Sukuk, including their respective costs, repayment obligations, foreign exchange implications, underlying asset requirements and accountability mechanisms.
This would enable legislators to consider not only the amount Nigeria intends to borrow but also the financing structures that can best support the delivery of the projects for which the borrowing is intended.
It goes without saying that Nigeria does not necessarily have a shortage of financing instruments.
What it urgently needs is a financing framework that restores confidence in the relationship between public borrowing and public benefit. Scaling up Sukuk, in both domestic and international capital markets, offers an opportunity to achieve this objective.
The relatively small Sukuk issuances undertaken so far have helped finance identifiable road infrastructure and demonstrated the instrument’s practical relevance to Nigeria’s development needs.
A substantial expansion of the programme could make a much greater contribution to infrastructure development, while broadening the investor base and strengthening project-level transparency.
All said, government borrowing should not merely create additional liabilities for future generations; it should create enduring assets that improve productivity, expand economic opportunities and raise living standards. Sukuk, properly structured and transparently administered, can help Nigeria move closer to that objective.
Uche Uwaleke, a financial Economist, is Director of the Nasarawa State University Institute of Capital Market Studies and President of the Capital Market Academics of Nigeria

Bayelsa Spends N13.2b on Salary-related Items in September
ShareFrom Mike Tayese, Yenagoa Bayelsa State Government over the weekend said the total salary-related items to civil servants in the...


OPay Provides Update on Planned NYSE IPO, Reaffirms Normal Business Operations
Share From Tony Nwachukwu, Lagos Fintech company OPay has announced the postponement of its planned public offering on the New...

Aba Commercial Smart City Celebrates COO, Mazen Kalassina at 39
ShareBy David Torough, Abuja Aba Commercial Smart City has celebrated its Chief Operating Officer (COO), Engr. Mazen Kalassina, on his...

Rebuilding Public Trust in Government Borrowing: The Case for Scaling Up Sukuk Financing in Nigeria
ShareBy Uche Joe Uwaleke The recent request by President Bola Tinubu to the National Assembly for approval to raise $20.52...

2027: Buba Yakub Mobilises Adamawa Support for Tinubu, APC
ShareFrom Yagana Ali, Yola The Director-General of the Nigerian Technical Aid Corps (NTAC), Rt. Hon. Yusuf Buba Yakub, has called...

2027: FOOG Women Coordinator Urges Nigerians to Support Tinubu’s Re-election Bid
ShareBy Francis Sadhere, Warri Chief (Mrs) Esther Orighomisan Okotie-Eboh, Coordinator of Felix Omagbemi Ogbe Group (FOOG) Women Support Group for...

Troops Neutralise 217 Terrorists, Rescue 349 Kidnap Victims, Arrest 333 Suspects in Oct
ShareBy David Torough, Abuja The Armed Forces of Nigeria (AFN) say troops neutralised 217 terrorists and other criminals, rescued 349...

2027: Tompolo Mobilises Support for Tinubu in Ogun, says Economy Stabilising
ShareThe Grand Patron of the PBAT Door-to-Door Movement, Government Ekpemupolo, has called on the people of Ogun State to massively...

Henry Okeke Commends Mbah for Clearing Pension Arrears in Enugu
ShareBy Raphael Atuu, Abuja Barrister Henry Nnanna Okeke, a member of the Governing Council of Enugu State Polytechnic, Iwollo, has...

2027: ADC Urges ECOWAS to Insist on Credible Elections in Nigeria
ShareThe National Chairman of the African Democratic Congress (ADC), Sen. David Mark, has urged the Economic Community of West African...