NEWS
Beyond 23 Per Cent MPR, Should CBN Reconsider 45 Per Cent CRR to Unlock Credit?

By Blaise Udunze
The last Monetary Policy Committee (MPC) meeting of the Central Bank of Nigeria (CBN) was its 307th meeting, held on September 21 and 22, 2026. The decision taken was to reduce the Monetary Policy Rate (MPR) from 26.
5 percent to 23 percent. The decision of the Committee brings back a question about how well monetary policy works in an economy that needs cheap credit.The 350-basis-point reduction happens to be a significant adjustment to the policy-rate signal. Also, keeping the Cash Reserve Requirement (CRR) at 45 percent for deposit money raises a difficult question.
Can Nigeria lower the price of money while maintaining a regulatory constraint that limits the funds banks can deploy?In this case, the question is particularly important at a time when inflation has moderated, foreign reserves have strengthened and the banking industry has completed a major recapitalisation exercise. One fact that is critical here is that if these developments point towards an improving macroeconomic environment and a stronger financial system, why should banks continue operating under such a demanding reserve requirement?
Nigeria may have taken steps to reduce the cost of borrowing without doing enough to ensure that more businesses and individuals can access loans.
At the September meeting that has now ended the MPC made a decision. The MPC chose to keep the CRR at 45 percent for deposit money banks. The MPC also kept the CRR for merchant banks at 16 percent. For non‑Treasury Single Account (non‑TSA) public‑sector deposits the CRR was set at 75 percent. Meanwhile, the CBN made another change. The CBN adjusted the Standing Facilities Corridor to be +50/-300 basis points around the MPR.
During the changes, the apex bank described the adjustment as an operational realignment. The apex bank said it aimed to strengthen monetary-policy transmission and restore the MPR’s primacy as the signal of monetary policy. In reality, this distinction matters so much to say because the decision was not necessarily a declaration that the broader monetary stance had become expansionary.
Instead, the apex bank’s move reflected an attempt to strengthen the transmission mechanism through which monetary policy decisions influence market interest rates and broader economic activity.
Meanwhile, one of the key central concerns remains whether the adjustment translates into cheaper, more accessible credit for businesses and households. The warning signs are already evident.
In its report, MPR Cut: Why Cheaper Loans May Not Come Soon, Premium Times examined the factors that could delay the transmission of the rate reduction to borrowers. The report highlighted the continued 45 per cent CRR as a constraint on banks’ capacity to expand lending and noted that existing loan agreements and differences in repricing schedules could delay the impact of lower policy rates.
This introduces an important asymmetry into the monetary-policy debate. Banks’ deposit costs may decline faster than the interest rates charged on existing loans, potentially improving their net interest margins before borrowers receive meaningful relief. In other words, a lower MPR may boost bank profitability before it shows up in the real economy.
The fact is, this is not necessarily evidence of misconduct by banks. Loan contracts have different maturities and repricing conditions, while lenders must account for credit risk, funding costs and the possibility of default. Nevertheless, it raises a legitimate policy question, which is to inquire if the purpose of recalibrating the MPR is to improve monetary-policy transmission, how quickly should the resulting benefits reach borrowers, and what prevents that from happening?
The CRR is key and central to this debate because it influences the amount of qualifying deposit liabilities banks must maintain as reserves with the CBN rather than deploy directly into loans and other assets.
A 45 per cent requirement does not mean that lending automatically falls by 45 per cent. This is to say that banks have different funding structures and CRR interacts with capital requirements, liquidity regulations and other prudential rules. In this case, it is important to clarify that the requirement imposes a substantial constraint on the deployment of qualifying deposits and can influence the economics of financial intermediation.
The CBN is therefore sending two signals simultaneously whereby the lower MPR suggests an adjustment in the direction of its policy-rate framework, and also the unchanged CRR indicates that it remains concerned about liquidity management and financial stability.
Both objectives are legitimate. The question is whether their combined effect is consistent with the level of credit expansion Nigeria needs. The debate becomes more compelling when the country’s improving external position and moderating inflation are considered.
In a separate report, Leadership questioned the continued retention of the 45 per cent CRR despite stronger foreign reserves and easing inflation. The report cited economists who argued that the CBN should reconsider the degree of liquidity restriction as macroeconomic conditions improve.
It also cited Chapel Hill Denham’s estimate that the CRR could cost the banking industry as much as N2.5 trillion annually in potential earnings. Looking at this, the figure, however, represents estimated foregone earning opportunities, not a guaranteed volume of new lending that would materialise if the reserve requirement were reduced. Nevertheless, it underscores the opportunity cost of keeping substantial funds tied up in compulsory reserves, particularly at a time when businesses are demanding more affordable credit.
The policy question is whether the benefits of that restraint continue to outweigh its potential costs to lending and investment.
Nigeria’s stronger external reserves offer another reason to reassess the balance. This is to say that higher reserves can improve external confidence and provide a buffer against foreign-exchange shocks, although they do not automatically eliminate domestic inflationary pressures. Similarly, moderating inflation creates room to reconsider the intensity of monetary restraint, but it must be made known that it does not mean that inflation risks have disappeared.
The CBN must therefore explain what conditions would justify a review of the CRR, what risks it believes still require the current level, and how it intends to balance liquidity control with productive credit expansion, as this calls for urgency.
Also, it is important to state that the issue extends beyond monetary policy to the effectiveness of banking-sector recapitalization, as the exercise raised N4.65 trillion. DataPro Limited’s assessment put the average capital adequacy ratio at 25.5 per cent and highlighted the challenge of translating stronger bank capital into more productive lending. The report also cited N2.9 trillion in loan write-offs, illustrating the importance of credit losses and asset quality.
These figures raise a fundamental question about what recapitalisation should achieve.
A stronger capital base improves a bank’s capacity to absorb losses and potentially support larger exposures. It does not guarantee that the institution will extend more credit to manufacturers, agricultural businesses, exporters or small enterprises.
Also, it is more critical that banks must still assess the probability of default, collateral quality, the enforceability of loan agreements, operating costs and the commercial prospects of borrowers. Hence, whilst these risks are high, additional capital may strengthen the balance sheet without producing a proportionate expansion in lending.
In addressing the challenges, it is key to note that the post-recapitalisation test should therefore extend beyond the capital raised and the number of banks meeting regulatory thresholds. Yes, it should also examine whether banks are expanding sustainable lending to productive sectors without compromising underwriting standards.
This is where the interaction between CRR and recapitalisation becomes particularly important. If banks have stronger capital positions but remain subject to a high reserve requirement, the CBN must consider whether its regulatory framework is sufficiently aligned with its expectations for private-sector credit growth.
The answer cannot simply be to demand more lending. The fact is that policymakers must also examine the conditions under which lending becomes commercially viable.
For small and medium-sized enterprises, this challenge is especially acute. It is very well established that businesses without substantial collateral, audited financial records or established banking relationships often face higher borrowing costs or outright rejection, even when their underlying operations are viable. Large corporations with stronger balance sheets and established relationships may negotiate more favourable terms, though they are always on banks’ bad books as defaulters.
Consequently, a lower MPR may improve conditions for some borrowers without significantly changing the credit environment for the businesses that need financing most.
The real test of monetary-policy transmission is therefore not whether the headline rate has declined, but whether the effective cost and availability of credit have improved.
It should be understood that there is also a limit to what monetary policy can achieve on its own. Nigerian manufacturers may benefit from lower working-capital costs, but expensive energy, foreign-exchange constraints, imported inputs and logistics costs remain significant determinants of production expenses. A cheaper loan cannot fully compensate for unreliable power or persistently high operating costs.
The CBN must consequently approach credit expansion as part of a wider economic framework. Monetary policy can influence the price and availability of funds, but its effectiveness depends on business conditions, credit infrastructure, the quality of borrowers and banks’ willingness to accept commercially reasonable risks.
This does not diminish the importance of the CRR. Rather, it makes the case for a more evidence-driven review of its application.
Instead, it supports an evidence-based review of how the policy is applied.
Rather than removing the requirement all at once, the CBN might look at a gradual adjustment. This could be linked to inflation expectations, how much liquidity is in the banking system, stability in foreign exchange markets and whether credit growth’s strong and well-managed.
The CBN could also explore incentives for lending to sectors. These incentives must be carefully built, with clear eligibility rules and strong monitoring to make sure they work as intended.
Such an approach would need safeguards as this would help ensure that the extra money flowing into the banking system goes towards productive investments rather than speculation or activities that do little to grow the economy. Meanwhile, there is a need to clarify here that reducing CRR does not guarantee that banks will lend the released funds to businesses.
They could instead favour government securities, foreign-exchange-related transactions or other assets offering more attractive risk-adjusted returns as this has continued to be a repeated pattern in the system.
The objective must therefore be to improve productive credit allocation, not simply increase liquidity.
The CBN should establish transparent conditions for reviewing the 45 per cent CRR and publish evidence showing whether its policy decisions are improving credit access. Part of the measures must involve evidence that should include effective lending rates, loan applications and approvals, actual disbursements, private-sector credit growth, and financing to small businesses, manufacturing, agriculture and other productive sectors.
The functionality of how interbank rates and Treasury bill yields behave should also be watched because that tells us how the new MPR framework is affecting financial‑market conditions. Stakeholders must look at these indicators together with the real borrowing costs that businesses and households experience.
If the policy‑rate signal improves but the effective lending rates stay high and the credit approvals do not grow, the CBN must find out why the transmission is failing. Is the issue the cost of funds, the CRR, the credit risk, inadequate collateral, weak competition or a mix of these reasons?
The answers should determine the policy response rather than an assumption that any single instrument can resolve the problem.
This is also the appropriate way to judge recapitalisation. In reality, banks should not be compelled to extend unsustainable loans merely to meet a credit-growth target. In situations like this, a stronger banking system should be capable of demonstrating how it supports productive economic activity, which is key, particularly where viable businesses face financing constraints.
Nigeria needs a monetary policy that controls inflation while allowing banks to lend to businesses that can grow the economy. The CBN is right to be concerned about inflation, exchange-rate pressures and financial stability.
But monetary instruments must be continually assessed against changing economic conditions. Clearly, a rule that requires banks to keep an amount of money on hand that is reasonable, in one situation should not stop being checked when the big economic conditions change.
The 23 percent MPR and 45 percent CRR can exist together inside a monetary-policy plan. The real question is whether the combined result helps the CBNs goals, for stability, investment and term economic growth.
If the MPR falls while the cost and availability of credit remain largely unchanged, Nigeria will have adjusted the price signal of monetary policy without adequately addressing the constraints on financial intermediation.
Following the developments thus far, the next phase must therefore go beyond announcing lower rates. Yes, in truth, it must demonstrate that stronger bank capital, improving macroeconomic conditions and better monetary-policy transmission are translating into sustainable financing for productive businesses.
Ultimately, this must be made clearly known that the success of the 23 percent MPR will not be determined by the announcement itself. The real truth is that success will depend on whether the Nigerian entrepreneur, manufacturer, farmer and small‑business owner can obtain credit that’s affordable, easy to reach and lasting.
Until that happens, the question about the 45 percent CRR will not go away. Does monetary policy set up conditions that help growth or does the liquidity restriction still keep money from turning into credit that people can use or access?
Blaise, a journalist and PR professional, writes from Lagos and can be reached via: blaise.udunze@gmail.com
By Cleopas Agada
For seven years in the National Assembly, what has Benue South actually felt? For a man who rose to national prominence on the back of a national tragedy, Senator Abba Moro’s continued stay in the Senate has become a symbol of recycling, stagnation and non-performance.
Benue South, the Idoma nation, deserves more than a senator whose name is more associated with press statements than with projects, more associated with Abuja politics than with home development.
The Immigration Saga That Nigeria Cannot Forget
We cannot write the story of Abba Moro without writing the darkest chapter.
On March 15, 2014, as Minister of Interior under President Goodluck Jonathan, Abba Moro presided over the infamous Nigeria Immigration Service recruitment exercise.Young Nigerians, tens of thousands of unemployed graduates desperate for a job, were gathered in stadiums across the country. In their desperation, they paid N1,000 each for application. The organization was chaotic, inhumane and deadly. At the end of that day, over 20 innocent Nigerian youths died in stampedes in Abuja, Port Harcourt, Minna and other centres. Scores were injured.
It was a national scandal that drew international condemnation. Families are yet to recover. Till today, that tragedy remains a permanent stain on his public service record.
Seven Years of What Exactly?
Since 2019 when he went to the Senate, and now serving his second term (2019-2027), the question on the streets of Otukpo, Oju, Obi, Ado, Okpokwu, Apa, Agatu, Ohimini and Ogbadja is simple: Where are the dividends?
DAVID MARK vs ABBA MORO: THE REAL SCORECARD
To understand Abba Moro’s failure, look at what he inherited and what he did with it:
- The Otobi-Akpa Dam Legacy vs Failure:
Senator David Mark initiated the Dam at Otobi-Akpa as one of his greatest legacy projects. The purpose was clear: It was to stop the sufferings of the people from hardship faced from lack of water in Otukpo and its environs. It is even big enough to generate power for the area if it is completed and commissioned.
Today, the Federal Government is really not making further payments on that contract. The project is abandoned, contractor has left site. Otukpo people are back to buying water from tankers.
What has Abba Moro, as Senate Minority Leader who sits on budget committees, done to push for its completion? No motion. No lobbying. No budget insertion. He allowed a multi-billion naira legacy that would have solved water and power for Otukpo to die.
- The Oweto/Loko Bridge Legacy vs Failure:
David Mark lobbied for the Oweto/Loko Bridge which today serves as a gateway between the North and the South and opened up Agatu to the rest of Nigeria. Before this bridge, Agatu was hitherto a closed enclave. Today, economic activities flourish in Oweto market and other markets in Agatu.
What did Abba Moro do to consolidate? Nothing. No link roads from Oweto to interior Agatu. No federal market infrastructure. No strong voice to attract security intervention despite herdsmen killings in Agatu, Apa and Oju. The bridge is there, but the dividends that should follow are missing.
- Federal University of Health Sciences, Otukpo (FUHSO) vs No New Institution:
David Mark attracted FUHSO, bringing development, jobs and students to Otukpo. In seven years, Abba Moro cannot point to one new federal institution, cannot even secure a Teaching Hospital for FUHSO, and cannot attract one transformative signature project that has changed the economic fortune of Zone C. - Federal Jobs vs Handouts:
Mark used his position as Senate President to give Idoma sons and daughters federal appointments and national visibility.
Abba Moro’s model is handouts: motorcycles, grinding machines and N20,000. Our youths need jobs, functional skills acquisition centres linked to industries, and federal appointments. Compare to a fresher like Senator David Jimkuta of Taraba South who in less than two years empowered over 1,000 constituents with cars, motorcycles, refrigerators and business tools. Benue South has one of the highest rates of unemployment in the North Central.
- Legislative Silence and Disconnected Leadership:*
In the 9th and 10th Assembly, his legislative contributions have been largely pedestrian. No landmark bill for the economic liberation of Benue South, no strong advocacy that has brought federal intervention to killings in Apa, Agatu and Oju. A senator should be at home, but Abba Moro’s politics is Abuja-centric.
THE JUDGEMENT TABLE FOR EVERY IDOMA SON AND DAUGHTER*
DAVID MARK ACHIEVEMENTS ABBA MORO FAILURES
FUHSO: Established Federal University in Otukpo No Institution: No new federal institution in 7 years
Oweto/Loko Bridge: Opened up Agatu, gateway North-South, boom in Oweto market Failed to Consolidate: No link roads, no security for Agatu/Apa
Otobi-Akpa Dam: Initiated dam to stop water hardship in Otukpo, big enough to generate power Abandoned Dam: FG stopped payments, contractor left, Otukpo back to tanker water. No motion from Minority Leader to revive it
Federal Appointments: Gave Idoma jobs and national voice Handouts: Motorcycles and N20k, no jobs
Respected Zone C Nationally Abuja Press Statements
Benue South Needs a New Voice
The Idoma nation is blessed with brilliant, younger, more dynamic leaders. Idoma Renaissance, led by Johnson Ogwuche and Philip Okoh, has made it clear: “It is no longer business as usual. Any non-performing lawmaker will not be voted back.”
2027 is not far. Senator Abba Moro has served as Minister and two terms in Senate. It is time to go home, rest, and allow a new generation with fresh ideas, clean hands, and genuine love for the land to take Zone C to the promised land.
Benue South cannot afford another four years of motion without movement.
The Coordinating Minister of Health and Social Welfare, Prof. Muhammad Pate, said Non-Communicable Diseases (NCDs) have become one of the fastest-growing segments of Nigeria’s disease burden, requiring urgent health system readiness.
Pate said this on Thursday in Abuja at the unveiling of a book on Nigeria’s NCDs and health reforms, organised by the Health Reform Foundation of Nigeria (HERFON).
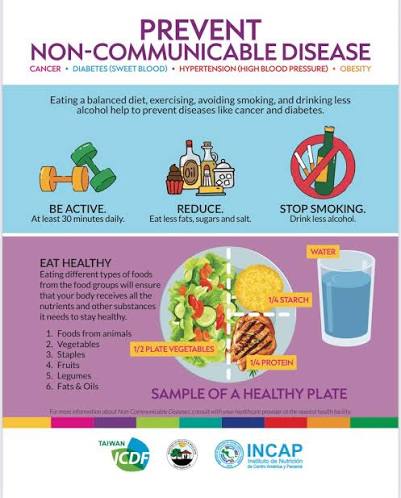
He said hypertension, diabetes, cardiovascular diseases, stroke, sickle cell disease, cancers and neurological conditions were increasing due to lifestyle changes and an ageing population.
The minister said Nigeria’s health reforms began more than 20 years ago, culminating in the National Health Act, with significant progress recorded in the last three years.
He said the Maternal and Neonatal Mortality Reduction Innovation Initiative (MAMI) had reduced maternal deaths by 22 per cent and newborn deaths by 10 per cent.
He added that a recent mini Demographic and Health Survey showed increased skilled birth attendance, antenatal care and contraceptive prevalence.
Pate said that malaria incidence had dropped to 15 per cent, the lowest in 20 to 30 years, based on survey statistics, but said HIV, tuberculosis and maternal mortality remained challenges.
He said the Federal Government, through the Health Sector Renewal Investment Initiative, had strengthened governance by bringing federal, state and local governments, civil society and the private sector together.
Pate said the federal health budget allocation had increased to six per cent from about three to four per cent previously, while states were being encouraged to increase their funding.
According to him, the government had expanded the primary healthcare system, retrained nearly 80,000 frontline health workers in three years and doubled admission quotas for medical and nursing students.
Pate said three of six world-class tertiary centres had been commissioned in Azare, Enugu and Benin.
He added that 10 world-class diagnostic centres equipped with MRI, CT scanners and catheterisation laboratories had been completed in partnership with MedServe and the Nigeria Sovereign Investment Authority (NSIA), including two recently completed in Ibadan and Bauchi.
He further added that the Federal Executive Council had recently approved more than N268 billion for major infrastructure projects at the National Hospital, Abuja.
Pate said the government was promoting prevention through the National Health Promotion Policy and the Know Your Numbers campaign, which had reached 10 million Nigerians with checks for blood pressure, blood sugar, cholesterol and prostate-specific antigen.
He said the government had also introduced Medipool, a group purchasing organisation, to ensure the availability of quality, affordable medicines at primary healthcare centres and improve treatment compliance for hypertension and diabetes.
Pate said affordability remained critical because NCDs required lifelong treatment, noting that more than seven million Nigerians had been added to health insurance in the last three years through the National Health Insurance Authority (NHIA).
He added that local pharmaceutical manufacturing was being expanded through the Presidential Initiative for Unlocking the Healthcare Value Chain (PVAC).
Pate commended HERFON and the book’s authors for providing analysis and recommendations to guide Nigeria’s response to NCDs.
Also speaking, the Chairman of HERFON’s Board of Trustees, Alhaji Idris Muhammed, said the foundation advocated better healthcare for Nigerians through policy advocacy, capacity building and evidence generation at local, state and national levels.
He said HERFON had a presence in all 36 states and the Federal Capital Territory (FCT) and had contributed to major health sector achievements, including the enactment of the National Health Act, 2014.
Muhammed said the book was the product of months of review by more than 70 subject experts from Nigeria, South Africa, the Middle East, the United Kingdom and the United States.
“The book tells us where we are, what we are doing wrong and what we must do right to stem the tide of NCDs,” he said.(NAN)
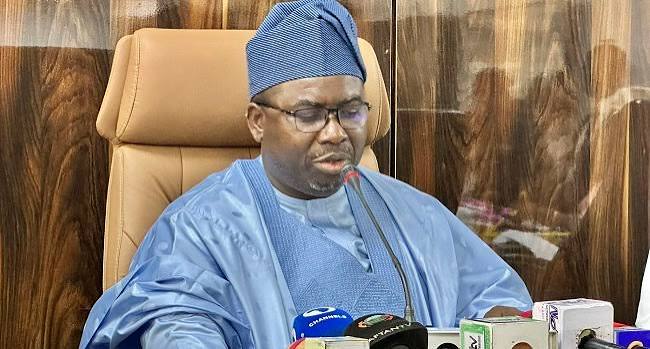
The Independent National Electoral Commission (INEC) has reaffirmed its commitment to strengthen collaboration with the National Orientation Agency (NOA), security agencies and other relevant stakeholders to ensure credible, peaceful and transparent general elections in 2027.
The Chairman of INEC, Prof.
Joash Amupitan, gave the assurance on Thursday in Abuja at the commencement of the Nationwide Grassroots Mobilisation for the 2027 General Election, organised by NOA.The theme of the campaign was, “Your Vote, Your Voice, Our Future: Say No to Apathy, Vote Buying and Violence”.
Amupitan said the forthcoming general election offered the country an opportunity to demonstrate its democratic progress and establish its readiness to conduct elections that would command national and international confidence.
“The upcoming 2027 general election presents us with an opportunity to demonstrate to Africa and the world that Nigerian democracy has matured beyond measure.
According to him, Nigeria must use the election to demonstrate its preparedness in electoral administration, technological development and operational transparency.
Amupitan said INEC was committed to strengthening its institutional capacity and improving the systems required to deliver credible elections across the country.
He said that achieving the objective would require cooperation between the electoral commission, NOA, security agencies, civil society organisations and patriotic Nigerians.
The INEC chairman identified technology as a critical component of the electoral process, explaining that the commission is strengthening its technical infrastructure to protect electoral data and improve the efficiency of election administration.
He said that the large number of registered voters and the geographical challenges associated with conducting elections across Nigeria made the effective application of technology indispensable.
Amupitan said that there had been occasions when Nigerians waited several days for election results to be announced, adding that INEC is working to prevent such delays through improved technological arrangements.
He said the commission had secured the procurement of additional bimodal voter accreditation systems to strengthen its capacity to accredit voters during the 2027 general election.
He said that INEC was also expanding hardware redundancy and deploying additional equipment to ensure that technological challenges did not disrupt electoral operations.
The chairman said the equipment was being delivered, tested and configured ahead of the elections as part of measures to strengthen the commission’s operational readiness.
Amupitan acknowledged public concerns over the technological challenges experienced during the 2023 general elections, saying INEC is taking steps to address the issues and improve its systems.
He said the commission was working to ensure that accreditation equipment and other technological facilities were sufficiently available across the country before the next presidential election.
According to him, improving the reliability of electoral technology remains central to the commission’s efforts to strengthen public trust and ensure that every eligible voter can participate without unnecessary difficulties.
The INEC chairman also identified the protection of polling-unit results as a non-negotiable aspect of the commission’s transparency framework.
He said that the commission was strengthening the electronic transmission and publication of polling-unit results, including the uploading of Form EC8A, to promote transparency and allow citizens to verify electoral outcomes.
Amupitan said comprehensive cybersecurity measures were being deployed to protect INEC’s networks, data transmission channels and digital systems against cyberattacks and unauthorised interference.
He said that technological advancement had introduced new challenges, particularly with the emergence of artificial intelligence and other sophisticated digital tools that could potentially be exploited to undermine electoral credibility.
The chairman said that the proper use of Form EC8A would help safeguard the accuracy, authenticity and reliability of results recorded at polling units.
He said the initiative was being implemented in compliance with Section 29 of the Electoral Act 2026 and was designed to improve the transparency and integrity of political parties’ candidate nomination procedures.
According to him, the digital process will help prevent discrepancies between candidates who emerged from party primaries and the names subsequently submitted to the commission for elections.
He said that following the conclusion of party primaries, the details of nominated candidates were being uploaded to the portal to ensure that the commission maintained accurate records of candidates selected through the recognised party processes.
Amupitan said the digital system would also allow INEC to reflect changes arising from successful appeals after party primaries, thereby ensuring that only duly recognised candidates are included in the nomination process.
He said that the initiative was intended to address past challenges involving the substitution of candidates, arbitrary exclusions and disputes over party nominations.
The INEC chairman said strengthening digital nomination procedures would improve accountability, reduce administrative errors and reinforce confidence in the electoral system.
In his keynote address, Malam Lanre Issa-Onilu, Director-General of NOA, said the agency was committed to helping Nigerians understand the electoral process and appreciate their responsibilities as citizens.
According to him, civic education must be presented in ways that make participation in elections understandable and relevant to the everyday lives of Nigerians.
He said that voter apathy weakened democratic representation by allowing a smaller proportion of citizens to determine decisions that affected the wider population.
The NOA boss also condemned electoral violence, noting that it threatens lives, silences voters and damages relationships within communities long after elections have ended.
He said that political competition should never be allowed to result in the loss of lives or the destruction of peaceful relationships among Nigerians.
He further cautioned against allowing political disagreements to destroy the bonds between neighbours, emphasising that peaceful coexistence remains essential to national unity and democratic development.
Issa-Onilu also urged Nigerians to reject financial inducements capable of influencing their electoral choices, stressing that the country’s collective future should not be determined by temporary personal benefits.
He said that convictions would guide the grassroots mobilisation campaign as the agency intensified efforts to educate citizens on the importance of responsible political participation.
The NOA director-general called on stakeholders, community leaders and other relevant institutions to support the campaign by promoting peaceful conduct, voter awareness and respect for democratic principles.
He said that the success of the 2027 general elections would depend on INEC’s preparedness, and also on the willingness of citizens to participate responsibly and reject practices capable of undermining electoral credibility.(NAN)

Senator Abba Moro: It is Time to Go Home
ShareBy Cleopas Agada For seven years in the National Assembly, what has Benue South actually felt? For a man who...

NCDs Fastest-growing Disease Burden in Nigeria — Pate
ShareThe Coordinating Minister of Health and Social Welfare, Prof. Muhammad Pate, said Non-Communicable Diseases (NCDs) have become one of the...

2027: Adeleke Inaugurates Aare Asejere’s Campaign Council
ShareFrom Ayinde Akintade, Osogbo The Governor of Osun State, Senator Ademola Adeleke, yesterday charged newly inaugurated members of the Osun...

INEC Seeks Stakeholders’ Collaboration for Credible, Peaceful Elections
ShareThe Independent National Electoral Commission (INEC) has reaffirmed its commitment to strengthen collaboration with the National Orientation Agency (NOA), security...

Reps Reject Child Marriage, Demand Protection of Girl Child
ShareBy Ubong Ukpong, Abuja The House of Representatives on Thursday unanimously called for urgent and coordinated actions to protect Nigerian...

Court Awards N125, 000 Cost against Odumodublvck
ShareAn Abuja High Court on Wednesday awarded N125, 000 against a rapper, Tochukwu Ojogwu, popularly known as “Odumodublvck”, for asking...

Hunger Changed My Mind, Timini Egbuson on Embracing YouTube movies
ShareNollywood actor Timini Egbuson has reflected on his changing perception of YouTube movies, joking that he might have struggled financially...

Peller Announces Livestream with Peter Obi
SharePopular Nigerian TikTok streamer, Hamzat Adelaja, popularly known as Peller, has announced an upcoming livestream with the presidential candidate of...

Nigeria’s inflation drops from 15.39 Per Cent to 14.63 Per Cent in September
ShareBy Tony Obiechina, Abuja The National Bureau of Statistics (NBS) on Thursday disclosed that Nigeria’s inflation has eased from 15.39...


Senate Oders Investigation into Corps Member’s Death in Enugu
ShareBy Tambaya Julius, AbujaThe Senate has ordered an investigation into the death of a National Youth Service Corps (NYSC) member,...