NEWS
FRSC Moves to Enforce Uniform Colour for School buses


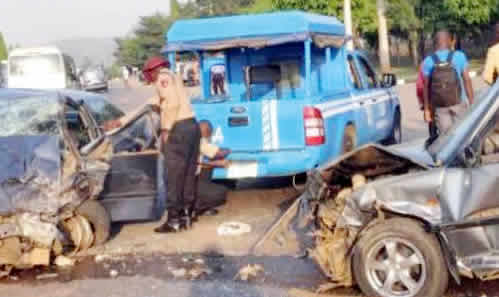
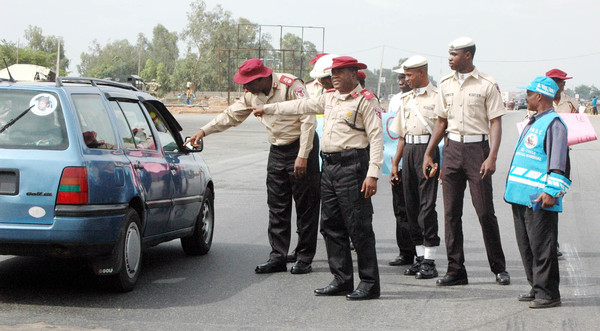
The Federal Road Safety Corps (FRSC) says it will soon commence the enforcement of a uniform colour for school buses in the Federal Capital Territory (FCT).Mr Gora Wobin, the FRSC, FCT Sector Commander, disclosed this on Saturday in Abuja, during a stakeholders town hall meeting with school proprietors.
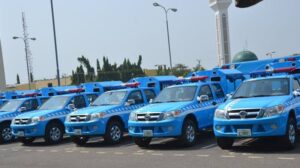
The town hall meeting was organised by the Lugbe unit command, of the FRSC, headed by its commander, Mr Ameen Adewale. Wobin said that the move became necessary for easy identification of school buses by the FRSC, adding that it will augur well for proprietors to paint their school buses in the approved colour.“The fact that we have not enforce it does not mean we are not going to do it, the information has been in public domain since 2014,” he said.According to him, there is a prototype of the colour in the headquarters of the FRSC, while advising them to check in order to be sure of the approved colour.He said that identification of school buses was keyed, noting that the FRSC had had to intercept a bus with kidnapped school children, with the driver claiming they were going on excursion.The sector commander added that if it were to be a uniform coloured bus, the corps would have been able to detect immediately.He then urged the proprietors to ensure a uniform colour for their school busses.“It is advisable for all our school buses to be painted in an approved school colour, it is a law and a regulation by the government and must be obeyed,” he said.He said that rather than use force, the FRSC had embraced dialogue with school owners to paint their busses in the approved colour.Wobin said that this would go a long way to help in ensuring that any school bus driver caught flouting the law, could be allowed to go and drop the children off and then arrested soon after.He however said that if school proprietors had any strong reasons why the law must not be implemented, they were free to write to the appropriate authority.According to him, there is an urgent need for proprietors to also install speed limit devices in all their school buses.He explained that the speed limit device would help to reduce the wear and tear of the vehicles, and also help to conserve fuel consumption.”It is a must for these proprietors to install the speed limit device,” he said.Wobin noted that some of the drivers of these buses do not obey traffic rules, warnng that such act will no longer be tolerated.The New Agency of Nigeria (NAN) reports that one of the concerns raised by the proprietors included the slashing of the cost of the speed limit device.They also pleaded with the FRSC to ensure it organised periodic workshop for their drivers, as it would assist them in doing the right thing.The school proprietors present at the meeting included Tithemi International School, AYES school, Diamond Standard Basic School and Britarch Montessori School, Lugbe, among others. (NAN)




From Sylvia Udegbunam, Enugu
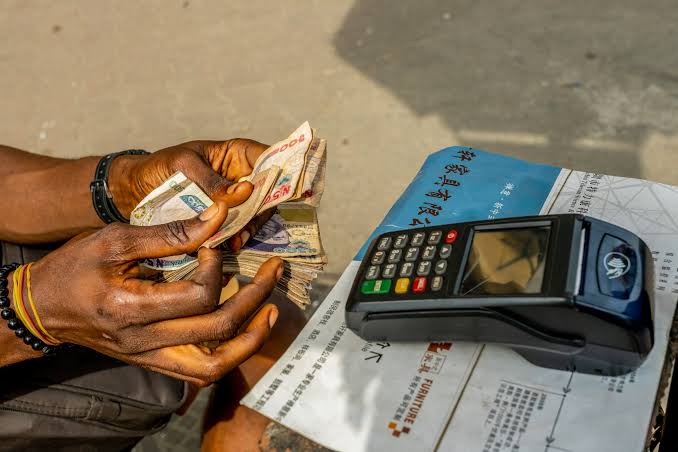
The Enugu State Police Command has arrested a 28-year-old male suspect, Michael Ayisa, for allegedly robbing a female Point-of-Sale (POS) operator of ₦200,000 at gunpoint and recovered a pistol and an expanded 9mm ammunition shell.
On 18 October 2026, at about 12:26 p.
m. , Police Operatives attached to Udenu Division, supported by members of the Neighbourhood Watch Group, arrested the suspect at Obollo-Afor, Udenu LGA, following a report that he had robbed the victim at her shop along Old Orba Road, Uhulor, Obollo-Afor in Udenu LGA, on 17 October 2026, at about 9:00 a.m.In a statement signed by the Police public relations officer Enugu State command headquarters Daniel Ndukwe said that Preliminary investigations indicate that the victim raised the alarm as the suspect fled, allegedly threatening to shoot anyone pursuing him. A Beretta-like pistol and an expanded 9mm ammunition shell were recovered from him. The suspect confessed to the crime during interrogation.
The suspect will be arraigned in court upon conclusion of investigations.
The Commissioner of Police, CP Mamman Bitrus Giwa, commends the operatives for the successful operation and acknowledges the complementary support provided by the Neighbourhood Watch Group. He reiterates the Command’s commitment to combating crime and urges residents to promptly report suspicious activities to the police and other recognised security agencies.
By Uche Joe Uwaleke
The Nigeria Capital Market Master Plan 2.0 (NCMMP 2.0), covering 2026-2036, is a commendable and ambitious undertaking that deserves recognition.
The Securities and Exchange Commission (SEC), the sponsors, FSD Africa and the Foreign, Commonwealth & Development Office (FCDO), and the consortium of consultants led by Genesis Analytics and Bourse Consult deserve commendation for investing the expertise, resources and collaborative effort required to articulate a strategic vision for Nigeria’s capital market over the next decade.
The aspiration to build a diverse, efficient, transparent and innovative capital market that positions Nigeria as a regional financial hub and mobilizes the capital needed to drive wealth creation and a US$1 trillion economy by 2030 is quite compelling.
There is every reason to be confident that the plan can make a meaningful contribution to Nigeria’s economic transformation.However, the success of a masterplan of this magnitude will depend not only on its aspirations and proposed reforms, but also on the realism of its time horizon, its alignment with national development priorities, the inclusiveness of its formulation and the strength of the institutional arrangements for its implementation.
On these critical considerations, the Nigerian experience offers important lessons, including from Malaysia’s latest Capital Market Masterplan.
One fundamental question is whether a ten-year implementation horizon, spanning 2026-2036, is the most appropriate framework for the NCMMP 2.0.
While a long-term vision is necessary for transforming a capital market, the implementation programme must be anchored in a timeframe that is sufficiently realistic, measurable and aligned with the country’s prevailing economic policy framework.
In this respect, Malaysia’s Capital Market Masterplan 2026-2030, launched on 9th March 2026, offers a useful model.
Malaysia has adopted a five-year implementation horizon within a broader 20-year vision extending to 2045.
This approach distinguishes between the long-term destination and the medium-term actions required to get there.
It allows policymakers and market participants to translate strategic ambitions into specific, time-bound priorities, assess progress against measurable milestones and recalibrate interventions in response to changing economic conditions without losing sight of the overarching vision.
Nigeria would have benefited from a similar architecture.
The country already has a National Development Plan for 2026-2030, situated within the longer-term Nigeria Agenda 2050.
A capital market masterplan covering 2026-2030 would therefore have provided a natural and coherent framework for aligning capital market reforms with national economic priorities, while preserving a longer-term perspective towards 2050.
This is not merely a question of administrative convenience or the choice of a more convenient planning cycle.
It goes without saying that the capital market does not operate in an economic or policy vacuum.
Its development is profoundly influenced by macroeconomic stability, fiscal and monetary policy, the investment climate, public-sector borrowing, pension and insurance regulations, infrastructure development and the government’s broader economic priorities.
The market can mobilize capital, facilitate investment, deepen financial inclusion and support enterprise growth, but it cannot independently overcome policy constraints that lie beyond its institutional reach.
Indeed, the NCMMP 2.0 document itself provides a compelling reason to take this alignment seriously.
It acknowledges that the first Capital Market Master Plan, covering 2015-2025, achieved only 63 percent of its planned activities, with just two of its 21 macro-objectives fully achieved by the end of 2025, while the remaining 19 were at varying stages of execution.
A revised masterplan was subsequently developed in 2021 to reflect market realities, while the absence of alignment with Nigeria’s national development blueprints weakened broader buy-in from policymakers. These are significant lessons.
They suggest that ambitious targets and extensive stakeholder engagement, however valuable, cannot substitute for a planning framework that is integrated with the national policy environment and commands sustained political and institutional ownership.
It would therefore have been prudent to make the NCMMP 2.0 a medium-term implementation plan for 2026-2030, explicitly aligned with the National Development Plan for the same period, within a longer-term capital market vision extending to 2050.
Such an arrangement would have offered a more direct connection between capital market reforms and national economic objectives, made it easier to assign responsibilities to relevant government institutions, and strengthened accountability for delivery.
It would also have provided a natural opportunity for a comprehensive review at the end of 2030, when the next phase could be developed in light of the country’s economic performance, policy direction and progress in capital market development.
A ten-year plan is not inherently inappropriate, but its effectiveness depends on how well its implementation cycle is integrated with the national planning system.
The concern, therefore, is not the ambition of the NCMMP 2.0, but the risk of creating another planning horizon that may not adequately correspond with the policy framework upon which its success depends.
The second issue concerns the breadth and inclusiveness of the stakeholder consultation undertaken in developing the masterplan.
The engagement of 18 institutions, including regulators, government agencies, market infrastructure providers and industry associations, is commendable and demonstrates an appreciation of the diverse interests that shape the capital market.
The contributions of these stakeholders are indispensable because they bring practical knowledge of regulatory constraints, market infrastructure, operational challenges and the commercial realities confronting capital market participants.
Nevertheless, the composition of the consultation process raises an important question: where was the academia?
In Nigeria, the Capital Market Academics of Nigeria provides an umbrella platform for researchers and academics working on financial markets and related issues.
Its omission from a process of this strategic importance represents a significant gap in the range of perspectives brought to bear on the masterplan.
Academia is not merely an observer of the capital market or a commentator on policies formulated elsewhere.
It has a distinctive contribution to make through independent research, empirical analysis, critical evaluation of policy assumptions, assessment of international experience and examination of the economic models underpinning strategic targets.
Academics can interrogate whether proposed interventions address the market’s most binding constraints, whether the assumptions underlying projected outcomes are defensible, and whether the proposed sequencing of reforms is consistent with available evidence.
They can also identify unintended consequences, test alternative policy options and recommend appropriate indicators for measuring progress.
These contributions are particularly important when a masterplan seeks to deliver structural changes over several years.
Targets relating to market capitalization, capital mobilization, investor participation, product diversification and the development of Nigeria as a regional financial hub must rest on credible assumptions and a clear understanding of the relationship between policy interventions and expected outcomes.
An independent academic perspective can strengthen the analytical foundations of these targets and help distinguish between aspirations that are desirable and outcomes that are realistically achievable under specified conditions.
It can also enhance the credibility of the plan by ensuring that its underlying logic is open to rigorous scrutiny.
The value of academic participation, therefore, lies not in adding another institution to a consultation list, but in introducing a complementary form of expertise that regulatory, governmental and industry stakeholders may not independently provide.
Equally important is the distinction between consulting stakeholders individually and bringing them together to deliberate collectively.
Association-based consultations are useful for eliciting the views of specific professional groups, understanding sector-specific challenges and ensuring that participants can speak candidly about their interests.
However, separate consultations alone are insufficient for an undertaking as consequential and cross-cutting as a national capital market masterplan.
It is a no-brainer that the interests of regulators, exchanges, institutional investors, market intermediaries, issuers, infrastructure providers, policymakers and researchers inevitably intersect.
A reform intended to address one segment of the market may have implications for another, while measures that appear desirable from the perspective of an individual institution may create implementation difficulties elsewhere.
These interdependencies are not always fully apparent when stakeholders are consulted in isolation.
A more robust process would have combined the individual consultations with a national stakeholder conference convened specifically to deliberate on the draft masterplan before its finalization.
Such a conference would have provided a structured platform for presenting the proposed strategic priorities, testing the assumptions underlying the recommendations, identifying inconsistencies and resolving competing perspectives.
It would also have enabled stakeholders to assess the feasibility of proposed reforms collectively, clarify institutional responsibilities and build a shared understanding of the sequencing required for effective implementation.
Crucially, it would have given the academic community an opportunity to scrutinize the evidence and analytical framework underpinning the document alongside those responsible for regulation, policymaking and market operations.
This collective deliberation should ideally have preceded the SEC’s National Capital Market Conference at which the final masterplan was unveiled for implementation. The distinction is crucial.
A conference convened after a document has been finalized is principally an opportunity to communicate its contents, mobilize support and discuss implementation.
A conference convened while the document is still a draft can influence its substance, improve its analytical quality and generate a stronger sense of collective ownership.
The latter is particularly valuable when implementation depends on numerous institutions, many of which have different mandates, priorities and resource constraints.
Consultation should not be treated simply as a procedural requirement to be completed before a document is published; it should be an integral part of policy design, with a demonstrable opportunity for participants to shape the final outcome.
There is also a broader lesson to be drawn from the Malaysian example.
Malaysia’s experience reinforces the importance of continuity between successive masterplans.
Each iteration of its capital market strategy builds on the experience of the preceding one, while responding to changing economic and market conditions.
Nigeria should similarly institutionalize periodic, transparent assessments of implementation, supported by clearly defined indicators, responsible institutions, realistic timelines and public reporting.
The experience of the first NCMMP demonstrates why this matters.
A plan can articulate the right aspirations and still fall short if responsibility is diffuse, coordination is weak, resources are inadequate or implementation is insufficiently monitored.
The new masterplan should therefore be accompanied by a credible delivery framework that establishes measurable annual milestones, provides for regular independent evaluation and makes it possible to distinguish between completed activities and reforms that have produced tangible economic outcomes.
All said, the NCMMP 2.0 deserves to be welcomed as an important statement of ambition and a potentially significant instrument for the development of Nigeria’s capital market.
The SEC and its partners have undertaken a substantial assignment, and the country’s financial system stands to benefit if the plan’s reforms are effectively implemented.
The observations raised here should not detract from that achievement; rather, they are intended to strengthen the prospects of success by drawing attention to lessons that Nigeria’s own planning experience and Malaysia’s latest masterplan bring into sharper focus.
Indeed, a more deliberate connection between the NCMMP 2.0 and the national development planning cycle, and broader participation by the academic community would help strengthen both the substance of the plan and the legitimacy of its implementation.
Uche Uwaleke is Nigeria’s renowned Professor of Capital Market and the Director of the Nasarawa State University Institute of Capital Market Studies
By Tambaya Julius, Abuja
Interswitch and its banking partners are stepping up efforts to promote tokenised card payments, which could make transactions faster, more secure and convenient for Nigerians.
The initiative was highlighted at an Interswitch tokenisation documentary press briefing in Lagos at the weekend, where the company and participating banks discussed plans to expand contactless payments through compatible smartphones and other devices.
The Managing Director, Payment Processing and Switching, at Interswitch Purepay, Akeem Lawal, described tokenisation as a major development that could change how Nigerians pay for goods and services.
“Where we are going is just tapping,” Lawal said, explaining that the future of digital payments would involve customers completing transactions by tapping their devices rather than going through several steps.
Tokenisation replaces sensitive card details with a substitute identifier known as a token, helping to protect customers’ original card information during transactions.
With compatible devices and payment terminals, customers can make payments through digital wallets and authenticate transactions using security features such as fingerprints or facial recognition.
“You will have reduced the friction of transacting significantly,” Lawal said, noting that the technology could simplify payments and reduce the time customers spend completing transactions.
He said Nigeria’s payment system had evolved over the years through innovations such as interbank automated teller machine switching, point-of-sale services and online transactions, which have transformed how people access and transfer money.
According to him, tokenisation could build on these developments by making digital payments more seamless and convenient.
Under the conventional bank transfer process, customers typically open a banking application, enter an account number and follow several steps to complete a transaction. Tap-to-pay technology, however, allows customers to authenticate themselves and pay by tapping a compatible device on a payment terminal.
The Executive Director of Wema Bank, Tunde Mabawonku, highlighted the potential of mobile devices to make payments easier across different aspects of daily life, particularly public transportation and international travel.
“This same phone, I should look to tap to make payments on the BRT bus. I should look to tap to make payments on the blue line, the red line,” Mabawonku said, pointing to opportunities to extend contactless payments to transport services.
He said the technology could make mobile phones more versatile payment tools, allowing customers to use a single device for transactions across different services.
Beyond smartphones, the technology could also support smartwatches and other compatible wearable devices, giving consumers more options for contactless payments.
The Head of the Digital Banking Division at GTBank, Jimmy Banjoko, said Nigeria was still at an early stage of adopting tokenised payments but noted that changing consumer behaviour could encourage wider acceptance.
He pointed to the growing preference for digital and contactless transactions as evidence that consumers were becoming more receptive to alternative payment methods.
“We see that is a signal to suggest that innovation can go in this line because market behaviour is already tending towards this contactless,” Banjoko said.
He expressed optimism that tap-to-pay transactions could become more common as customers gradually move from app-based transfers to contactless payment options.
However, wider adoption will depend on effective implementation, the availability of compatible devices and payment terminals, and consumers’ willingness to embrace the technology.

Enugu Police Arrest 28 Year Old Suspect for Robbing POS Operator
ShareFrom Sylvia Udegbunam, Enugu The Enugu State Police Command has arrested a 28-year-old male suspect, Michael Ayisa, for allegedly robbing...

Peter Obi Has Nothing to Offer as President — Shettima
ShareBy Tony Obiechina, Abuja Vice-President Kashim Shettima has criticised the presidential candidate of the Nigeria Democratic Congress (NDC), Peter Obi,...

NCMMP 2.0: The Gaps in National Alignment and Inclusive Consultation
ShareBy Uche Joe Uwaleke The Nigeria Capital Market Master Plan 2.0 (NCMMP 2.0), covering 2026-2036, is a commendable and ambitious...

Interswitch, Banks Push Tap-to-Pay for Faster Transactions
ShareBy Tambaya Julius, Abuja Interswitch and its banking partners are stepping up efforts to promote tokenised card payments, which could...


ADC, Shettima In Hot Exchanges Over Atiku Economic Plan
ShareBy Tambaya Julius Abuja The African Democratic Congress (ADC) Presidential Campaign Council has criticised Vice-President Kashim Shettima over his remarks...

Phone-Tapping Saga: Abuja Court Orders El-Rufai to Open Defence
ShareBy Tambaya Julius, Abuja A Federal High Court in Abuja on Monday dismissed a no-case submission filed by former Kaduna...

WAHO, ECOWAS Countries Move to Tackle Health Worker Shortages, Brain Drain Through Regional Retention Plan
ShareBy David Torough, Abuja The West African Health Organization (WAHO) has called for stronger regional collaboration and practical policy interventions...

Ekpo Empowers Women, Supports Hospital Patients at 50
ShareBy Tambaya Julius, Abuja The All Progressives Congress (APC) flag bearer for Karu/Gitata Constituency in the Nasarawa State House of...

Ebola: Bayelsa Activates Emergency Response
ShareFrom Mike Tayese, Yenagoa The Bayelsa state government has intensified disease surveillance and emergency preparedness following reports of an Ebola...

FG Disburses N38.93bn to Tertiary Institutions
ShareBy Tony Obiechina, Abuja The Federal Government has disbursed N38.93 billion to 166 public tertiary institutions nationwide under the Needs...