BUSINESS
Fuel Hike: FCT Motorists, Commuters Groan as Fares Rise Again

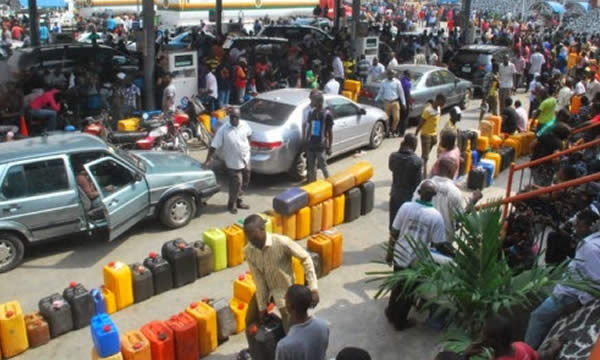
Many motorists, commuters and road transport workers in the Federal Capital Territory (FCT) have expressed concern as petrol prices rise again, pushing up transport fares and household expenses.
The latest increase followed Dangote Petroleum Refinery’s fourth upward review of its petrol gantry price since Aug.
21.The refinery raised the price from N1,265 to N1,350 per litre, an N85 increase, representing 6.
7 per cent.The new price, effective Sept. 12, has triggered fresh pump-price adjustments across filling stations in the FCT.
Checks in Abuja showed that MRS outlets were selling petrol at N1,395 per litre, while NIPCO outlets were selling at N1,430 and Mobil outlets at N1,400.
However, other outlets were selling the product at prices approaching N1,450 per litre, depending on location and prevailing supply costs.
The development had raised concerns among vehicle owners and commuters, with transport operators saying increased fuel costs were putting additional pressure on their businesses.
Udoh Daniel, a motorist in Abuja, described the latest increase as unbearable, saying the rising price of petrol was affecting household finances.
“Imagine buying petrol at N1,414 per litre. My cousin told me that it is selling for N1,450 presently in Dawaki,” Daniel said.
He said the continuous increases were making it increasingly difficult for motorists to maintain their vehicles and meet other financial obligations.
Favour Adeniji, another Abuja resident, said the latest increase was coming at a difficult period for families following the resumption of academic activities.
“Our children have just returned to school, and we are struggling to pay their fees when the petrol price increase was slammed on us.
“This is ill-timed. The government and other people responsible for this are not considerate at all because it has created additional pressure,” she said.
A civil servant, Ali Salisu, also expressed concern over the effect of rising petrol prices on workers whose salaries had not increased in line with the cost of living.
“Salaries are not increasing, yet the price of petrol keeps rising and pushing up the price of everything else.
“This administration is pushing workers and ordinary Nigerians to the edge.
“There is a popular saying that if you chase a goat to a brick wall, it will have no choice but to hit back at you.
“I hope the government is not gradually pushing Nigerians to their limit,” Salisu said.
For commuters, the impact is being felt directly through higher fares on some routes within Abuja and its suburbs.
Commuters from satellite towns and other surrounding communities going to the city centre now spend more on daily transportation than they did before the latest petrol increase.
Commuters travelling from the Masaka-New Nyanya-Ado-One Man Village axis to the city centre said fares had increased from N1,000 to N1,200.
Similarly, commuters from Kubwa, a satellite town to Federal Secretariat, Wuse and Berger now pay N1200, instead of N1000
The additional N200 per trip could translate into thousands of naira in extra monthly expenditure for workers who commute to Abuja every weekday.
Transport workers have also expressed concern that higher fuel costs are reducing their daily earnings because a larger proportion of their revenue is now spent on petrol.
A taxi driver, Salem Ogbe, said operators were caught between increasing fares to cover their expenses and protecting passengers from additional financial pressure.
“I am tired of this job because there is hardly any profit left,” Ogbe lamented.
He said drivers could not increase fares every time petrol prices rose because passengers were also struggling with higher living costs.
According to him, transport operators were therefore being forced to absorb part of the increase, despite the additional cost of fuelling and maintaining their vehicles.
“The situation is particularly challenging for drivers who cover long distances daily and consume significant quantities of petrol before returning home,” he said.
A private vehicle owner, Collins Ejiga, said the increase had eaten deep into his savings and was affecting his livelihood.
“When the pump price was N1,265 per litre, I was buying 50 litres for #63,250, which lasted me for a week.
“With the latest increase to N1,450, I am buying the same quantity for N72,500, which is about a N10,000 increase. The pressure is becoming unbearable,” Ejiga lamented.
Some motorists said that to mitigate the pressure, they were reducing unnecessary journeys, combining multiple errands into single trips and considering public transportation to control their monthly expenses.
Some commuters on the other hand, said they faced the difficult choice of paying higher fares, walking longer distances or waiting for cheaper means of transportation.
The increase has also raised concerns among traders and small business operators because higher transportation costs could increase the cost of moving goods from markets and distribution centres.
Some of the business owners said they had no choice but to increase the prices of their wares to cover the increased cost of transportation.
Meanwhile, economic experts had warned that increased transportation and production costs could eventually feed into the prices of food and other essential commodities.
They contended that the development could further compound the challenges faced by Nigerians who were grappling with rising living costs.
The latest adjustment is the fourth upward review of Dangote Refinery’s petrol gantry price since Aug. 21, bringing the cumulative increase to N185 within the period.
Motorists and transport operators have urged stakeholders in the petroleum sector to ensure greater stability in petrol prices to enable households and businesses to plan their finances.
For FCT residents, the concern extends beyond the price displayed at filling stations, as each increase affects the cost of commuting, household budgeting and daily economic activities.
As motorists and commuters adjust to the latest increase, transport workers say further petrol price increases could create additional pressure on fares and the already stretched finances of passengers. (NAN)
By Raphael Atuu, Abuja
The Federal Ministry of Livestock Development has trained 200 sheep and goat farmers in Kano State on improved production practices as part of efforts to raise livestock productivity, strengthen food security and create sustainable livelihood opportunities for small-scale farmers.
The three-day training programme brought together beneficiaries from Fagge, Tarauni and Gwale Local Government Areas, who were trained in animal management, feeding, breeding, healthcare and other husbandry practices aimed at improving productivity and reducing losses.
The Permanent Secretary of the Ministry, Dr.
Chinyere Ijeoma Akujobi, who was represented by the Director, Department of Ruminant and Monogastric Development, Victor Egbon, said livestock development required more than the provision of animals, stressing the need to equip farmers with the knowledge and skills to manage their livestock effectively.According to her, interventions of this nature are designed to strengthen farmers’ productive capacity, improve household livelihoods and support the Federal Government’s efforts to increase livestock production and food security.
“The sheep and goat subsector occupy a particularly important position within Nigeria’s livestock economy. Small ruminants are accessible to a wide range of households, require comparatively modest start-up investment, adapt to diverse production environments, and provide meat, milk, skin and other products that contribute to household nutrition and income. Their relatively short reproductive cycles also make them an important instrument for improving household assets and livelihoods.
“The Federal Ministry of Livestock Development therefore considers small-ruminant development a strategic component of national food security, employment generation, poverty reduction, women’s economic participation, youth entrepreneurship and economic diversification,” she explained.
Dr. Akujobi added that the training combined theoretical sessions with practical demonstrations to enable participants to understand how proper feeding, breeding, animal health and general husbandry could contribute to healthier animals, improved productivity and increased income.
On her part, the Permanent Secretary, Kano State Ministry of Livestock Development, Hajiya Rabi Ibrahim Waya, commended the Federal Ministry’s intervention, saying the state would also undertake similar initiatives to strengthen livestock production and support farmers.
She stressed that Kano State would continue to explore opportunities to help farmers translate the knowledge acquired and productive inputs provided into sustainable economic activities.
The programme also featured contributions from relevant stakeholders, including the National Sheep and Goat Development Association of Nigeria (NASHGODAN) and the Africa Women in Animal Resources, Farming and Agribusiness Network, represented by Aisha Maidawa.
One of the beneficiaries, 33-year-old Afrahsiyya Idris, a person living with disability, was among the participants, demonstrating the potential of livestock farming to provide inclusive livelihood opportunities.
At the end of the training, the 200 beneficiaries received sheep and goats, animal feeds and stipends to support them in applying the knowledge acquired.
The intervention is expected to support beneficiaries in improving their farming activities, raising household income and contributing to increased sheep and goat production in Kano State.
The World Bank Group said it mobilised a record 112 billion dollars in private capital in fiscal year (FY) 2026, more than tripling the 35 billion dollars recorded in FY22.
Combined with the Group’s own financing, the mobilisation brought total financing and mobilisation in developing economies to well above 200 billion dollars during the fiscal year.
The bank announced this in a statement issued on Thursday in Abuja.
According to the statement, the bank mobilised more private capital in fiscal year 2026 than in any year in its history.
It said that the bank issued a record volume of guarantees, delivering on a goal shareholders and clients have pressed for years.
“This has put more private capital to work alongside its own financing and expertise in developing economies,” the statement said.
It said Private capital mobilisation to lower-middle-income countries rose from 14 billion dollars in FY22 to 37 billion dollars in FY26, while upper-middle-income countries increased from 12 billion dollars to 50 billion dollars.
The statement said that in low-income countries, private capital mobilisation remained at about three billion dollars.
“Mobilisation across Africa increased from approximately nine billion dollars to 22 billion dollars, representing an increase of nearly 150 per cent,” it said.
It attributed the increase to reforms introduced over three years to make the World Bank’s operations faster and simpler, and strengthen collaboration between its public and private sector arms.
“We brought the Group together in each country, with a single point of contact across our public and private sector work, and began developing integrated strategies for each country based on its needs and development priorities.
“The Private Sector Investment Lab complemented that effort, helping to identify the practical barriers holding back investment in developing economies and developed a work plan to address them.
“The group has pursued that agenda across the institution: improving the business and regulatory environment, expanding guarantees and local-currency financing, and addressing foreign-exchange challenges.
“It is also increasing equity tools, and advancing new ways for institutional investors to participate at scale,” it said.
The statement said that the World Bank Group issued no fewer than 25 billion dollars in guarantees during FY26, exceeding its annual target of 20 billion dollars by 2030, four years ahead of schedule.
It said the growth was led by the bank’s Guarantee Platform, established in 2024 to provide clients and investors with simpler access to guarantee products across the institution.
The statement said job creation remained a central priority for the bank, with 1.2 billion young people expected to reach working age in developing economies over the next 10 to 15 years.
It said only about 420 million jobs were projected to be created during the period, while the private sector currently provided nine out of every 10 jobs in developing economies.
The statement said the group’s jobs strategy was focused on investing in human and physical infrastructure, creating business-ready regulatory environments and helping the private sector scale.
It listed infrastructure and energy, agribusiness, healthcare, tourism, and value-added manufacturing as five sectors with the potential to generate investment and employment at scale.
It said in FY26, 55 per cent of total financing, including the group’s own account and mobilised capital, went to those five job-rich sectors.
“Private investment is also reaching lower-income economies, where regional and local investors are increasingly complementing global capital in financing businesses and supporting job creation.
“The World Bank is seeking to expand the number of investors participating through its originate-to-distribute(O2D) initiative, which aims to package and distribute investments to institutional investors.
“The initiative is intended to connect more long-term institutional capital with investment opportunities in developing economies, while broadening the sources of financing available for development,” it said.
It said that the objective was to mobilise more capital from more sources and direct greater amounts towards job creation and economic opportunities in developing economies.
Meanwhile, Ajay Banga, World Bank Group President, said that the FY26 achievements were made possible with the encouragement of the bank’s shareholders and clients.
“Three years ago, our shareholders and clients were clear: utilise World Bank Group financing and knowledge to mobilise more private capital and become a better partner to the private sector.
“We changed how we work to do that-faster, simpler, and as one World Bank Group.
The result is 112 billion dollars mobilised this year, more than three times where we started.
“But the number only matters if the capital goes where it can create opportunity and jobs, while continuing to remove barriers and expand the investor base and driving more capital into developing economies, ” Ajay said.(NAN)
The Nigerian stock market extended its positive momentum on Wednesday, marking the fifth consecutive bullish session.
The market’s upward movement was driven by gains in equities like: Sovereign Trust Insurance, Champion Breweries, Livestock Feeds, Learn Africa, Mutual Benefits and 29 other stocks.
The market capitalization increased by 0.
20 per cent, adding N315 billion to investors’ portfolio as the market opened at N158.399 trillion and closed higher at N158.714 trillion.Similarly, the All-Share Index (ASI) rose by 0.20 per cent, advancing by 487.
28 points to close at 244,791.79, compared to 244,304 51 recorded on Tuesday.Consequently, the market’s Year-to-Date return improved to 57.31 per cent.
Also, the market breadth closed positive with 34 gainers against 26 losers.
On the gainers’ chart, Sovereign Trust Insurance led by 9.69 per cent, closing at N2.15, Champion Breweries followed by 9.50 per cent, finishing at N10.95 while Livestock Feeds increased by 9.42 per cent, ending the session N7.55 per share.
Similarly, Learn Africa gained by 9.09 per cent, settling at N8.40 and Mutual Benefits advanced by 8.93 per cent, closing at N3.05 per share.
Conversely, Industrial and Medical Gases led the losers’ chart by 9.93 per cent, settling at N27.65, John Holt trailed by 9.88 per cent, finishing at N7.30 while Livingtrust Mortgage Bank lost by 9.84 per cent, ending the session at N2.84 per share.
Also, Fidson Healthcare declined by 9.19 per cent, closing at N72.65 and Royal Exchange dipped by 9 per cent, finishing at 91k per share.
Market activity strengthened during the session, with total volume traded rising by 27.23 per cent to 662.43 million shares, valued at N37.45 billion in 63,271 deals.
Sterling Nigeria led trading volume with 142.04 million shares, accounting for 21.44 per cent of the total.
Guaranty Trust Holding Company recorded the highest value traded at N5.27 billion, representing 14.07 per cent of the day’s total. (NAN)

Fuel Hike: FCT Motorists, Commuters Groan as Fares Rise Again
ShareMany motorists, commuters and road transport workers in the Federal Capital Territory (FCT) have expressed concern as petrol prices rise...

SharePost Recapitulation: NAICOM Holds First Quarterly Staff Meeting By Tony Obiechina, Abuja The Commissioner for Insurance, Olusegun Ayo Omosehin, at...
Livestock Ministry Trains 200 Sheep, Goat Farmers in Kano
ShareBy Raphael Atuu, Abuja The Federal Ministry of Livestock Development has trained 200 sheep and goat farmers in Kano State...

Trump Escalates Media Fight after Week of Setbacks
SharePresident Donald Trump has infused his ongoing feud with the White House press with a new level of acrimony. Journalists...
Nigeria; a Gen Z Will Soon Be President
ShareBy Prince Charles Dickson Two of my dogs fought with a bitterness I had never seen. The older one carried...

Wike, Performance and the Politics of Cross-Party Influence
ShareBy Raphael Atuu, Abuja Since assuming office as Minister of the Federal Capital Territory in August 2023, former Rivers State...
Niger 37 Tragedy: NSCDC Boss Must Go
ShareThe death of 37 detainees in the Nigeria Security and Civil Defence Corps (NSCDC) detention facility in Minna, Niger State,...

Shettima to Declare Editors’ Conference Open in Enugu Thursday
ShareVice President Kashim Shettima will on Thursday, September 24, 2026, declare open the 22nd All Nigeria Editors Conference (ANEC) of...

Police Raid FCT Crime Hotspots, Arrest 300 Suspects
ShareOperatives of the Federal Capital Territory Police Command have arrested approximately 300 persons, following a raid on identified crime flashpoints,...

Fidelity Bank Deepens Partnership with DAILY ASSET
ShareBy David Torough, Abuja Fidelity Bank Plc has reaffirmed its commitment to strengthening its partnership with DAILY ASSET Newspaper following...